
How Do Renovation Loans Work for Fix and Flip Investors
You've found a property with the right purchase price, a renovation plan that can create value, and a seller who won't wait through a conventional mortgage process. Then the bank's appraisal focuses on the home's current condition, not what it could be after the work. The deal fails before your contractor ever starts.
That's the gap renovation loans are designed to fill. For a fix-and-flip investor, the important question isn't, “How do renovation loans work?” It's whether the lender can verify the after-repair value, renovation scope, draw mechanics, and exit strategy well enough to fund the project without leaving you short of cash halfway through.
How Renovation Loans Work at a Glance
A renovation loan fits a property whose current condition does not reflect its planned value. An outdated kitchen, failed systems, or unfinished areas can prevent ordinary financing, even when the purchase price and completed value support the deal. The lender evaluates the documented scope, cost, schedule, and projected finished condition before approving the combined financing.
The structure combines acquisition and eligible renovation costs in one loan. Rehab proceeds remain in a controlled escrow account, then reach the contractor through draws after completed work is inspected. You do not receive the full construction budget at closing. That restriction protects the project and forces the budget to match actual progress.
The investor's basic deal model
For a fix-and-flip, underwriting connects four parts:
- Acquisition basis: The purchase price, eligible closing costs, and other permitted project expenses.
- Scope of work: The repairs, upgrades, materials, labor, permits, and sequence required to reach the approved finish.
- After-repair value: The supported market value after renovation, based on comparable completed properties rather than an optimistic resale target.
- Exit plan: The sale, refinance, or other defined repayment route for the short-term financing.
Bundling the purchase and renovation can beat arranging separate financing when the property needs substantial work before it can qualify for a conventional refinance or attract a buyer. It also puts the lender's review, budget, and collateral in one structure. The trade-off is tighter control. Scope changes, incomplete inspections, and cost overruns can delay draws or require additional cash from the investor.
The finished product must fit its market. This guide to kitchen remodeling in Austin Texas illustrates the same principle investors apply in Atlanta, Charlotte, Columbia, and other Southeast markets. A kitchen budget creates value only when its materials, layout, and finish level match the buyer profile and the rest of the property.
Where the lender controls risk
Renovation financing is not an open credit line. The lender ties proceeds to an approved budget, verified work, inspections, and the completed property's value. Government-backed renovation programs combine purchase or refinance financing with eligible improvements, subject to applicable county loan limits and appraisal requirements, as described in this FHA 203(k) overview.
Private investor loans use different terms and underwriting standards, but the discipline remains similar. The lender must see a credible property basis, a workable construction plan, draw timing that matches the job, and an exit that can repay the balance. If the scope is vague or the ARV is unsupported, a low rate will not rescue the deal.
Understanding ARV Underwriting and Loan Math
ARV, or after-repair value, is the number that makes renovation lending work. It represents the lender's estimate of what the property should be worth after the approved improvements are complete. That estimate comes from comparable renovated sales, neighborhood conditions, the proposed finish level, and whether the scope supports the finished valuation.
Don't start with the loan amount. Start with the completed property.
Build the value case before the budget
A practical ARV review follows this order:
- Identify comparable renovated properties. Look for properties that compete with the finished asset in location, size, layout, condition, and buyer appeal.
- Define the finish level. A luxury renovation in a workforce neighborhood may not produce a luxury exit value.
- Match the scope to the comps. If the comparable homes have updated kitchens, modern bathrooms, repaired systems, and finished exterior work, your scope needs to explain how the subject property will compete.
- Stress the resale assumption. Ask what happens if the sale takes longer, the buyer negotiates, or the final appraisal comes in below the target.
A lender then compares the requested loan against both total project cost and ARV. These are commonly described as loan-to-cost and loan-to-ARV. Loan-to-cost asks how much of the total project basis the lender is funding. Loan-to-ARV asks whether the completed property provides enough collateral support.
Practical rule: A strong ARV doesn't rescue an inflated renovation budget, and a low purchase price doesn't rescue weak comparable sales.
For a deeper explanation of the valuation concept, use this ARV guide for real estate investors before you submit a deal. The terminology is simple, but the underwriting consequences are substantial.
A replicable example
Assume the following project:
- Purchase price: $180,000
- Renovation budget: $65,000
- Closing and carrying costs: $15,000
- Total project cost: $260,000
- Supported ARV: $340,000
- Requested loan: $225,000
The lender would examine the requested loan against the total cost and the ARV. The investor would need to bring the gap between the approved loan and the eligible project basis, along with any costs the lender excludes or requires the borrower to pay directly.
The $75,000 difference between total cost and ARV is not automatically profit. It has to absorb financing costs, selling expenses, taxes, insurance, utilities, surprises, and the investor's desired margin. If the scope expands, the property takes longer to sell, or the ARV appraisal is conservative, that cushion can disappear quickly.
Renovation Loan Math at a Glance
| Component | Example Value | How Lender Uses It |
|---|---|---|
| Purchase price | $180,000 | Establishes the acquisition basis |
| Renovation budget | $65,000 | Determines the controlled rehab allocation |
| Closing and carrying costs | $15,000 | Shows the full project requirement |
| Total project cost | $260,000 | Supports loan-to-cost analysis |
| Supported ARV | $340,000 | Supports collateral and loan-to-ARV analysis |
| Requested loan | $225,000 | Determines the borrower's cash contribution and leverage |
The most common underwriting mistake is treating the maximum theoretical loan as the target loan. Experienced investors work backward from the exit, preserve liquidity for overruns, and reject projects where the completed value only works under perfect assumptions.
From Application to Draws and How Funds Are Released
A renovation loan can stall before closing when the lender cannot connect the purchase, scope, contractor, and exit plan. Submit the file as one project, not as a property loan with a rehab budget added later. The lender needs to understand what you are buying, what will change, who will perform the work, and how the finished asset will be valued.
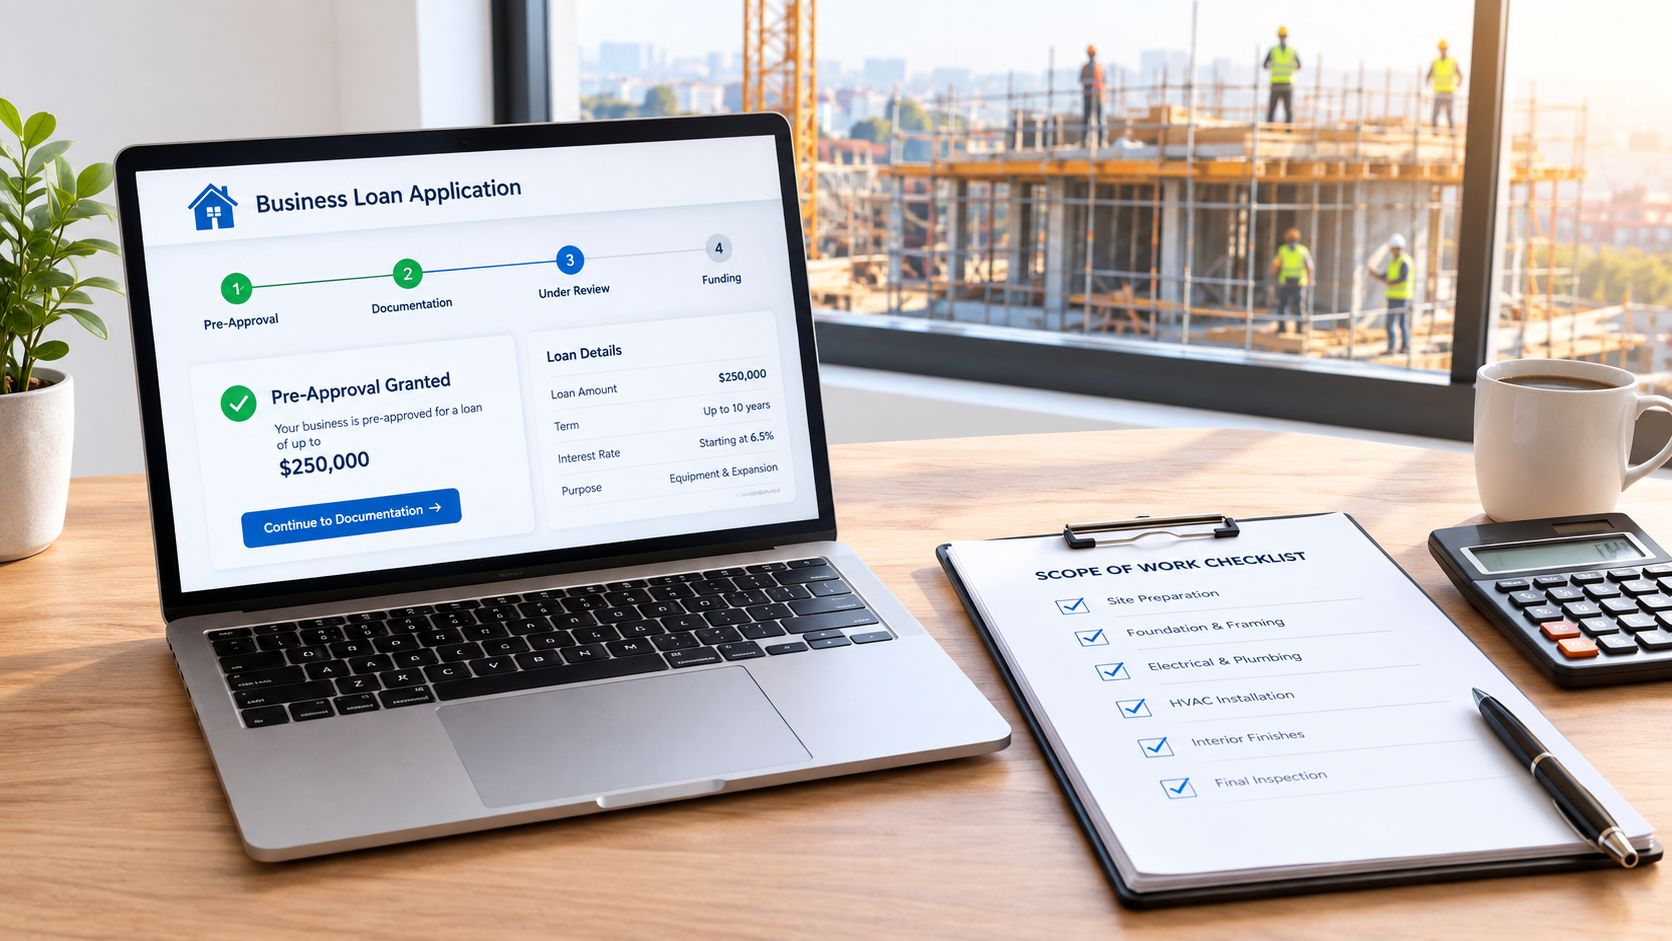
A credible submission usually includes the purchase contract, property details, contractor bid, line-item scope, project schedule, comparable sales, and a defined exit. Structural work may require plans, engineering information, permits, or related documentation. Gaps in any of these items create follow-up questions and can delay both underwriting and closing.
What happens before closing
The lender reviews the acquisition and renovation together.
- Property review: The current condition, location, title, insurance, and intended use are examined.
- Scope review: The lender checks whether the work is complete, realistic, properly priced, and consistent with the proposed finished value.
- Contractor review: Experience, insurance, required licensing, references, and available capacity affect approval.
- Valuation: The appraisal or internal valuation process considers the property after improvements, supporting the ARV-based loan structure.
- Loan structure: The lender sets acquisition proceeds, the rehab escrow, borrower contribution, reserves, and draw conditions.
The approval should also make the investor's cash requirement clear. A lender may fund the purchase and approved renovation budget while excluding certain closing, carrying, or change-order costs. Those items still require cash and should be included in the project's return calculation before the borrower commits.
Staged funding is common in renovation lending. The loan closes, work begins, and completed phases are inspected before the permitted funds are released. Private fix-and-flip lenders may use different forms and inspection procedures, but the operating logic remains the same: funds stay controlled until the project shows measurable progress.
How draws work in the field
The draw schedule should follow construction milestones, not arbitrary calendar dates. A contractor may complete demolition and rough work first, then move through systems, drywall, finishes, exterior work, and final punch-list items. At each approved milestone, the borrower requests a draw, the lender or inspector verifies the completed work, and the permitted amount is released.
Keep the lender's construction draw schedule guidance beside the contractor's schedule. Both should describe the same work in the same order, with amounts that match the approved budget.
A clean draw request includes current photos, invoices or receipts when required, a list of completed items, lien waivers where applicable, and an explanation for any variance from the approved scope. Submit documentation before the contractor runs short of funds. Waiting until payment is urgent often exposes missing paperwork at the worst point in the schedule.
Change orders need prompt handling. If hidden damage appears behind a wall, stop and document it before spending outside the approved budget. Ask the lender whether the change needs another inspection, how it will be approved, and which line item will fund it. Unauthorized work can create a payment dispute even when the work is necessary.
Timelines Closing Speed and What Can Delay Funding
A fast closing is possible when the deal file is complete and the third-party work moves quickly. Sims Ventures commonly targets an expedited closing process around 15 days, subject to appraisal, title, and underwriting completion, according to the publisher information provided for this article. That target isn't a promise that every renovation loan closes on that schedule. It's a reminder that speed depends on preparation.
The calendar usually breaks in one of two places. Either the lender cannot finish its review because the project information is incomplete, or a third party finds a problem that requires resolution before closing.
The items that control the clock
Appraisal timing can delay the file when comparable renovated sales are limited, the property is unusual, or the appraiser needs clarification about the proposed finished condition. A weak comp set also creates valuation risk, not just a scheduling problem.
Title issues can include unreleased liens, ownership discrepancies, probate complications, boundary concerns, or municipal matters. These problems rarely improve by waiting. Order title work early enough to leave room for corrections.
Scope quality matters because an incomplete bid creates follow-up questions. “Full renovation” isn't an underwriting scope. The lender needs enough detail to understand labor, materials, systems, finishes, permits, and sequencing.
Contractor documentation can stall an otherwise financeable project. Make sure the contractor can provide the requested insurance, licensing information, contract, budget, and schedule before you set an aggressive closing date.
A Southeast closing checklist
For projects in Georgia, North Carolina, South Carolina, or Texas, handle these items as soon as the property enters due diligence:
- Confirm municipal requirements: Ask the local building department what permits and inspections apply to the proposed work.
- Validate the contractor: Check availability, relevant project experience, insurance, and the ability to manage the job through completion.
- Order title work: Don't wait until the rest of the file is finished to discover a curative issue.
- Build the scope early: Separate repair necessities from optional upgrades so the lender can see the project logic.
- Prepare the valuation case: Organize comparable sales and explain why the finished property will compete.
- Confirm insurance: Make sure the property and construction activity can be insured under the lender's requirements.
Timing insight: The fastest file isn't the one with the most optimistic closing date. It's the one with the fewest unanswered questions.
Before locking a closing date, identify which items are controlled by you and which depend on the appraiser, title company, contractor, municipality, or lender. Then sequence your work around the slowest dependency.
Exit Strategies That Actually Work After Renovation
Renovation financing should be selected with the exit already in view. A flip loan makes sense when the finished property is positioned for sale. A bridge-to-rental structure makes more sense when the renovation creates a stable rental asset and the investor wants to refinance into longer-term debt.
The wrong exit can turn a profitable renovation into a liquidity problem. A property may look excellent after construction and still fail to support the refinance amount you need.
Sale versus DSCR refinance
A sale gives you a clean payoff when the buyer closes. It's usually the natural choice when the neighborhood supports strong resale demand, the renovation is designed for owner-occupants, or the projected sale proceeds justify releasing the asset.
A refinance keeps the property in your portfolio. Once the work is complete and the property is rent-ready, a DSCR lender evaluates the property's rental income and debt service rather than relying solely on traditional personal-income documentation. The investor may then use a cash-out refinance to redeploy available equity into another acquisition, subject to the new lender's valuation and rules.
For a broader explanation of the short-term financing role, review this guide to bridge loans in real estate. The key is to treat the bridge or renovation loan as a transition facility, not as permanent capital.
Decision matrix
| Decision factor | Sell after renovation | Refinance into DSCR debt |
|---|---|---|
| Primary objective | Realize the project margin | Retain the asset and build cash flow |
| Best property fit | Strong resale appeal and buyer demand | Durable rental demand and workable operating income |
| Repayment event | Buyer's closing proceeds | New loan closing proceeds |
| Main risk | Sale price, marketing time, transaction costs | Appraised value, rent support, debt coverage |
| Equity outcome | Converts property value into liquidity | Keeps equity invested and may allow redeployment |
| Tax planning | Requires review of sale treatment | Requires review of refinance and future disposition |
The decision should be made before construction starts. A resale renovation may prioritize visual impact and buyer appeal. A rental renovation should prioritize durable materials, operating efficiency, tenant demand, and rent support. Those are related goals, but they aren't identical.
If the sale depends on a narrow ARV premium, don't assume a refinance will rescue the deal. If the rental numbers only work at an aggressive valuation, don't assume a DSCR loan will provide the desired cash-out. Underwrite both exits early, then choose the one supported by the asset rather than personal preference.
Common Pitfalls and Smart Moves for Renovation Loan Success
A project can look profitable on paper and still fail before the first draw. The common causes are familiar: an inflated ARV, an incomplete scope, a contractor selected only on price, or an exit plan that exists only in the borrower's head. By the time the lender sees the problem, the deal usually contained it from the start.
Use a control for each risk.
Match each risk to a specific control
- Underestimated rehab budget: Divide the scope into labor, materials, permits, cleanup, and lender completion requirements. Have an experienced person challenge the estimate before submission, not after funds are committed.
- Unsupported ARV: Select renovated comparables that compete with the finished property in location, condition, layout, and buyer appeal. If the valuation depends on one unusually strong sale, reduce the ARV assumption or treat the deal as a warning.
- Weak contractor: Verify capacity, insurance, references, and the proposed schedule. A low bid becomes expensive when missed milestones delay draws, interest, and the resale.
- Poor draw planning: Tie every draw to observable completion. Organize progress photos, invoices, lien documentation, inspections, and approved change orders before requesting funds.
- No liquidity buffer: Keep cash available for excluded costs, delays, repairs outside the original scope, and lender-required contributions. A loan can fund the planned work without covering every dollar the project consumes.
- Unclear exit: Model both sale and refinance before closing. Each path needs its own valuation, rent, timeline, transaction-cost, and payoff assumptions.
When borrowing beats self-funding
Self-funding can fit a small project when cash remains available after closing and the opportunity cost of using it is low. It may also simplify a short renovation if staged draws would add more delay and administration than value.
Borrowing has a stronger case when bundling the purchase and rehabilitation preserves liquidity, makes a property financeable that standard financing cannot support, or keeps cash available for another project. The structure becomes dangerous when the borrower needs every draw for payroll, has no room for overruns, or depends on a best-case resale price.
Borrowers also use several funding sources for renovations. A 2026 mortgage consumer survey found that 63% of mortgage consumers planned to renovate within the next five years, 59% of future renovators intended to use savings, and 57% knew renovation costs could be rolled into a mortgage. Separate renovation market coverage reported that 34% of renovating homeowners used credit cards in 2026, compared with 29% the prior year, while the median planned renovation budget fell from $20,000 in 2025 to $15,000 in 2026 in its cited renovation market coverage.
Those figures do not make any funding method automatically suitable. The decision depends on borrowing cost, liquidity, project size, draw timing, and repayment certainty. Credit cards may create expensive short-term debt, while a renovation loan adds underwriting, inspections, interest, and payoff requirements. The right structure is the one the project can carry through completion and exit.
Before closing, confirm the purchase basis, ARV evidence, complete scope, contractor capacity, draw requirements, contingency plan, insurance, title status, and exit payoff. Sims Ventures provides fix-and-flip financing with purchase-plus-rehab structures, controlled renovation draws, bridge-to-DSCR pathways, and advisory support for investors in Georgia, North Carolina, South Carolina, and Texas. Visit Sims Ventures to test the financing structure against the actual ARV, budget, timeline, and exit.
