
What Is Debt Service Coverage Ratio and Why It Matters
You're standing in front of a duplex with a rent roll in one hand and a loan quote in the other. The property appears to work, but once you account for vacancy, operating costs, taxes, insurance, principal, and interest, one question remains: can this asset comfortably pay for itself?
That's the question debt service coverage ratio answers. In rental underwriting, DSCR compares the property's operating income with the debt it must pay, helping a lender decide whether the proposed loan fits the asset's cash flow. It also gives you a practical way to screen a deal before spending time on an application.
The Number Lenders Care About Most
A rental property can look attractive from the curb and still fail under the loan math. A duplex may have solid rents, a favorable purchase price, and a borrower with strong experience, but the property still has to generate enough income to support the proposed debt.
That's where debt service coverage ratio, or DSCR, becomes the first serious filter. The basic calculation is net operating income divided by total debt service. Major lenders commonly use thresholds around 1.20x to 1.35x for conventional commercial real estate loans, according to JPMorgan's explanation of DSCR in real estate.
A ratio of 1.25x means the property produces 25% more annual NOI than required for principal and interest payments, while 1.00x means income exactly matches scheduled debt payments. At 1.00x, there's no built-in room for repairs, vacancies, collection problems, or an unexpected increase in operating costs.
Why the property comes first
In a conventional loan conversation, you may expect the lender to begin with your salary, tax returns, credit profile, or employment history. Those items can matter, but an asset-based rental loan starts with a different question: does the property's income support the loan?
That distinction matters for investors whose personal income is variable, self-employed, or difficult to document in a traditional format. The lender is evaluating the property as an income-producing asset, not asking whether you can cover a shortfall from a paycheck.
The Federal Reserve found that DSCR at origination for securitized real estate generally fell between 1.2 and 2.4, illustrating how lenders have historically looked for a meaningful cash-flow buffer in institutional markets. Its research paper on commercial real estate underwriting places the ratio in a broader lending context, beyond small rental investors.
Treat DSCR as a planning tool
A weak DSCR isn't always a reason to abandon a property. It may indicate that the loan amount is too large, the projected rent is too conservative, the operating budget is incomplete, or the financing structure needs adjustment.
Run the ratio before you approach a lender such as Sims Ventures. Once you know the property's coverage, you can make a more informed decision about price, reserves, and whether the deal belongs in your portfolio.
What Debt Service Coverage Ratio Actually Means
In plain English, DSCR measures how many times a property's net operating income can cover its annual debt obligations.
The numerator is net operating income, or NOI. Start with the property's gross rental income and other recurring property income. Then subtract normal operating expenses, such as property management, maintenance, insurance, property taxes, utilities paid by the owner, and a vacancy or credit-loss allowance. NOI excludes mortgage payments and depreciation because the calculation is designed to measure property operations before financing and noncash accounting charges.
The denominator is total debt service. For a rental property, that generally means the required annual principal and interest payment on the proposed loan. Depending on the lender's method, the calculation may also include escrowed taxes and insurance, often described as PITIA, principal, interest, taxes, insurance, and association dues where applicable.
DSCR tells the lender whether the property earns enough to cover its loan, before your W-2, your side hustle, or your reserve account ever enter the conversation.
NOI is not the same as rent
Suppose a property collects substantial monthly rent. That figure alone doesn't tell you whether the asset qualifies. A landlord must account for the income that may not arrive and the expenses required to keep the property operating.
A property with high rents but heavy maintenance, management, insurance, or tax costs may have less NOI than expected. Conversely, a modestly rented property with disciplined expenses can produce stronger coverage.
Debt service includes more than interest
New investors sometimes look only at the interest portion of a payment. DSCR is stricter because the property must support the full scheduled debt obligation. That includes principal repayment, not just the cost of borrowing.
A 1.00x DSCR is the break-even point, and anything below 1.00x indicates that the property's cash flow doesn't cover scheduled payments. Commerce Bank's DSCR overview describes the same core test as cash flow available for debt service divided by total annual principal and interest.
The formula is simple:
DSCR = Net Operating Income ÷ Total Debt Service
The work lies in using realistic income, complete expenses, and the actual proposed loan payment.
How the DSCR Formula Works Step by Step
Build the calculation in the same order an underwriter would.
Start with property income
Add the rent from each unit. Then include recurring ancillary income, such as parking, laundry, storage, or pet fees, if the lender accepts and can verify those sources. Next, subtract a vacancy and credit-loss allowance, even if the property is currently occupied.
After that, subtract operating expenses. Include management, repairs, maintenance, insurance, taxes, utilities paid by the owner, association dues, and other recurring costs. The result is NOI.
Calculate annual debt service
Take the proposed monthly principal-and-interest payment and multiply it by the number of payment periods in the year. For example, a $2,500 monthly P&I payment creates $30,000 in annual debt service.
If the lender includes taxes and insurance in the denominator, add those annual amounts as well. The key is consistency. Don't compare NOI for one period with debt service for a different period, and don't leave required loan costs outside the calculation.
Divide NOI by debt service
A property producing $45,000 in NOI against $30,000 in annual debt service has a 1.50x DSCR. In other words, the property generates one and a half times the cash flow required for the loan payment.
Formula in words: Property operating income after operating expenses, divided by the property's complete annual loan obligation.
That ratio doesn't guarantee a loan approval. Lenders may also review appraisal support, property condition, title, reserves, borrower experience, loan-to-value, and the reliability of the income. But DSCR tells you whether the basic repayment engine is working.
Use the Sims Ventures DSCR loan calculator to organize the inputs, then verify the assumptions against the lender's underwriting definition before relying on the result.
Worked Examples With Real Rental Numbers
The underwriting difference becomes clear when the same rental property carries two different loan structures. The figures below use the stated rent, expense, purchase, rate, and term assumptions. Payment results can vary with amortization, escrow treatment, and rounding, so use them as illustrations rather than approval promises.
Example A, stronger structure
A $250,000 duplex produces $2,800 per month in gross rent, or $33,600 annually. Applying an 8% vacancy allowance subtracts $2,688, leaving effective rental income of $30,912.
Monthly operating expenses total $550, equal to $6,600 annually. The income calculation is:
- Gross annual rent: $33,600
- Less vacancy allowance: $2,688
- Effective rental income: $30,912
- Less operating expenses: $6,600
- Estimated NOI: $24,312
At 75% LTV, the loan amount is $187,500. A 7.25% rate over 30 years produces a monthly principal-and-interest payment of approximately $1,279, or about $15,348 annually. Dividing the estimated NOI by annual P&I gives a DSCR near 1.58x, before the lender adds any required treatment of taxes and insurance.
From a private rental lender's desk, this structure has room between property income and scheduled debt service. That cushion does not guarantee approval, but it gives the file more tolerance if operating results come in below the initial projection.
Example B, more aggressive borrowing
Keep the property and operating assumptions unchanged, then raise borrowing to 90% LTV, apply an 8.50% rate, and use a shorter amortization period. The loan amount rises to $225,000, while the higher rate and faster repayment increase annual debt service.
Under that shorter amortization assumption, the ratio can fall close to the 1.05x range. The property is near break-even, so vacancy, repairs, or the lender's treatment of taxes and insurance can quickly weaken the qualification.
| Input / Metric | Example A, Solid | Example B, Borderline |
|---|---|---|
| Purchase price | $250,000 | $250,000 |
| Gross monthly rent | $2,800 | $2,800 |
| Vacancy assumption | 8% | 8% |
| Monthly operating expenses | $550 | $550 |
| Estimated NOI | $24,312 | $24,312 |
| LTV | 75% | 90% |
| Interest rate | 7.25% | 8.50% |
| Amortization | 30 years | Shorter amortization |
| Approximate DSCR | Near 1.58x before PITIA adjustments | Near 1.05x |
The property did not change. The debt structure did. A higher balance, higher rate, and shorter amortization push the denominator upward quickly, even while rent remains constant.
Run your assumptions through the Sims Ventures DSCR loan calculator, then confirm how the lender defines income, expenses, taxes, insurance, and debt service before using the result in a loan proposal.
What Lenders Consider a Good DSCR
A “good” DSCR depends on the property, loan program, documentation, reserves, and the lender's risk tolerance. The practical underwriting question is simple: how much room remains after the property pays its scheduled debt service? Higher coverage gives the lender more protection if actual performance falls below the projection.
At 1.00x, the property's NOI covers scheduled debt service exactly. There is no operating cushion. One vacancy, a delayed rent payment, or a material repair can create a funding gap. From a private lender's desk, break-even coverage is a warning sign, not a comfortable structure.
Conventional commercial lenders often look for coverage above break-even, with thresholds commonly falling around 1.20x to 1.35x, as described by JPMorgan's DSCR resource. In practical terms, a ratio in that range means the property produces more cash than the scheduled debt requires. The extra amount is the buffer that absorbs weaker rent collection or higher operating costs.
Why private lenders may look for more room
Private rental lenders may structure loans differently from banks. Interest-only periods, stated-income approaches, transitional properties, higher debt usage, and shorter timelines can change the risk profile. Those features may lead an underwriter to prefer additional coverage or stronger collateral support.
There is no universal private-lender cutoff. Each lender sets its own guidelines and may review reserves, borrower liquidity, property condition, lease quality, appraisal support, and whether the income is established or projected. A property with a solid ratio can still require more documentation if its income history is thin or its condition needs work.
Review the documentation and eligibility factors commonly requested for rental financing in these DSCR loan requirements.
How underwriters test the cushion
An underwriter may reduce the rent used in the calculation or apply a conservative expense assumption to test whether the ratio survives a vacancy shock. The exact adjustment depends on the loan program and lender. Projected rent is not the same as collected rent, so the underwriter tests the income that can reasonably support repayment.
A stronger DSCR may support a larger loan amount, more favorable pricing, lower reserve pressure, or a smoother approval process. None of those outcomes is automatic. The lender still validates the entire transaction, including the property, borrower, collateral, and debt structure.
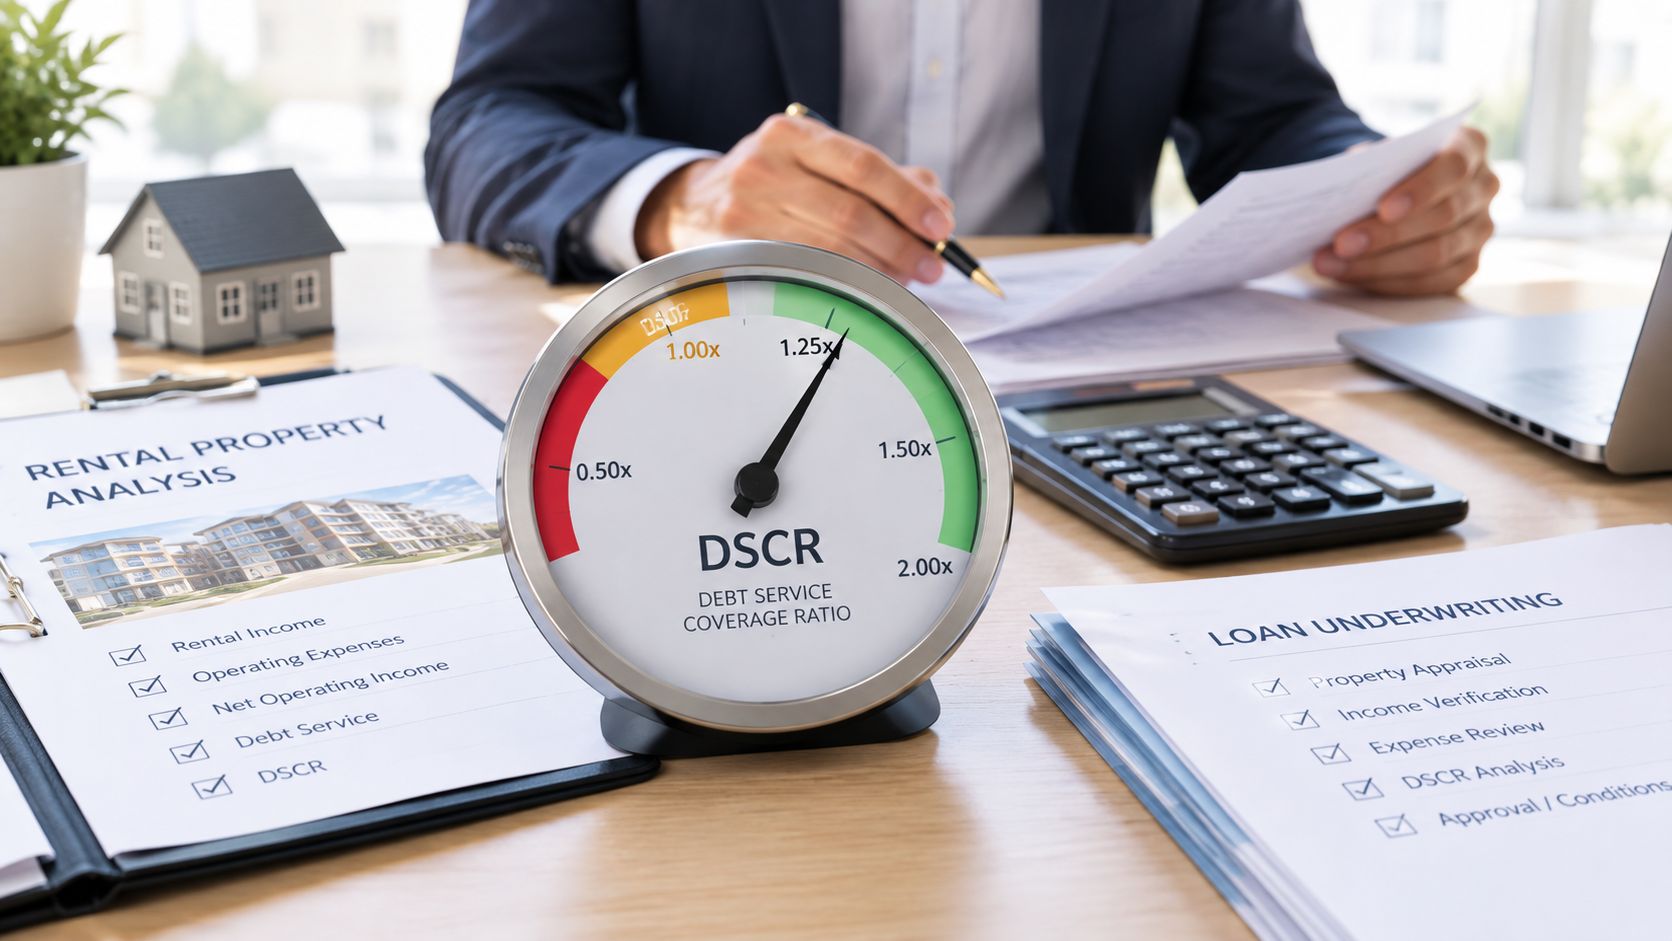
Levers that improve coverage
- Raise dependable income: Market-supported rent increases can raise NOI when the higher rent is realistic and documentable.
- Control operating costs: Better maintenance planning or a carefully reviewed management agreement can reduce expenses without weakening operations.
- Reduce the payment: A lower rate, longer amortization, or smaller loan balance reduces debt service.
- Buy with margin: A lower purchase price improves the relationship between property income and financing.
- Wait for stabilization: Completed repairs, stronger occupancy, and documented operating history can make the income profile easier to underwrite.
DSCR is a risk conversation, not a magic cutoff. It shows how much breathing room the property has before a lender must rely on reserves, collateral, or the borrower's other resources.
Practical Ways to Improve Your DSCR
You can improve DSCR by increasing NOI, reducing annual debt service, or combining both. The best choice depends on how much cash you're willing to invest and how quickly you need the loan to close.
Improve the numerator
Raising rents to market is often the cleanest operational lever. If a unit is materially under market, a documented rent adjustment can improve NOI without changing the property's debt. The increase must be supportable, because an underwriter won't treat an aggressive projection as collected cash.
Expense control works on the same side of the formula. Review management charges, owner-paid utilities, recurring service contracts, insurance, and maintenance patterns. Cutting a legitimate expense helps, but stripping out necessary repairs can make the projection look better while making the property riskier.
Reduce the denominator
A rate buydown can lower the monthly payment, but discount points require cash at closing. Extending amortization can also reduce required monthly principal and interest, though it may increase total interest paid over the life of the loan. Increasing the down payment reduces the loan balance, but it ties up capital that could otherwise fund improvements or another acquisition.
A refinance can help after the property has seasoned, operations have stabilized, or the market offers more workable terms. Waiting may improve the debt structure, but it also means carrying the current financing longer and accepting the opportunity cost of delayed liquidity.
Model the trade-off before choosing
Suppose a property's initial DSCR is 1.10x. A rent increase, expense reduction, lower rate, or smaller loan may move the result toward 1.25x, but the arithmetic depends entirely on the property's NOI and payment. Don't assume that a small rate change or rent adjustment will create the same result on every deal.
Use a simple sensitivity grid:
- Rent case: Current rent, supported market rent, and a conservative rent figure.
- Expense case: Actual expenses, normalized expenses, and a lender-conservative budget.
- Debt case: Proposed payment, lower-rate payment, and reduced-balance payment.
- Exit case: Hold the loan, refinance after stabilization, or sell after the planned business objective.
DSCR also affects cash-out room and portfolio scaling. A property with stronger coverage may support a refinance that returns capital, while a weak ratio can force you to leave equity in place.
A bridge-to-DSCR strategy follows the same logic. Short-term financing can fund acquisition or improvements, then long-term rental debt becomes the exit once the property is stabilized and its cash flow supports the payment. The transition only works if you underwrite the future DSCR before taking the bridge loan.
Why DSCR Shapes Your Deal Structure
A rental property can look attractive on paper and still fail to support the loan you want. DSCR often shapes the financing structure before you choose the final loan terms.
A private lender starts with the property's acceptable NOI, then works backward from the target DSCR. If the program requires a particular coverage level, that target limits the annual debt service the property can carry. The interest rate, amortization period, and loan balance then determine how much financing fits within that payment limit.
The relationship is straightforward:
Maximum supported debt service = NOI ÷ target DSCR
A stronger ratio gives the lender more room, and it gives you more choices. You may be able to borrow closer to the property's value, keep more cash available for improvements, or create room for a cash-out refinance. Those options remain subject to separate limits for LTV, property type, appraisal value, reserves, and program eligibility.
The rate you refinance into shapes the payment, so review current DSCR loan interest rates before sizing the deal.
Bridge financing needs an exit plan
Investors often use short-term, interest-only financing when a property needs repairs, lease-up, or operational stabilization. That loan may fit the acquisition phase, but the permanent refinance still has to pass the DSCR test using stabilized income and the new payment.
Before closing the bridge loan, estimate the likely refinance payment. Then test projected rent after applying realistic vacancy and operating expenses. If the stabilized property cannot support the permanent debt, the bridge loan can leave you with a difficult exit instead of a completed strategy.
Underwrite that exit before you close, not after the renovation is finished.
Portfolio growth depends on repeatable coverage
One property may survive because you contribute personal cash. A growing portfolio cannot depend on that approach indefinitely. Each new asset adds another payment competing for the same capital and attention. Consistent DSCR clearance helps you distinguish acquisitions that can operate independently from those that rely on optimistic assumptions.
| DSCR Range | Likely Loan Sizing | Cash-Out Refi Room | Rate Positioning | Best Use Case |
|---|---|---|---|---|
| Below 1.00x | Usually constrained by insufficient property cash flow | Limited | Challenging | Rework the deal before applying |
| Around 1.00x | Near the property's payment capacity | Little room for weakness | More restrictive | Only with a clear restructuring plan |
| Around 1.20x to 1.25x | Often aligned with common underwriting targets | Potentially workable, subject to other limits | Program-dependent | Conventional rental financing review |
| Above the target band | More flexibility, subject to LTV and collateral | Greater potential flexibility | May support stronger terms | Stabilized acquisitions and refinancing |
The same idea applies beyond rental underwriting. The Federal Reserve reported U.S. household debt service payments at roughly 11.3% of disposable income in the fourth quarter of 2025, according to the Federal Reserve household debt service series. Debt-service pressure affects complete household balance sheets, not only individual rental properties.
Run DSCR before submitting every offer. Build a one-page worksheet covering rent, vacancy, operating expenses, the proposed loan payment, and a conservative exit scenario. If the ratio is weak, adjust the structure before the lender identifies the problem.
Sims Ventures offers DSCR purchase and refinance financing for qualifying one-to-four-unit rental properties, along with bridge-to-DSCR pathways and deal-structure guidance for investors in Georgia, North Carolina, South Carolina, and Texas. Review your property's cash flow and financing options by visiting Sims Ventures.
