
Loans for Rehab: A Practical Investor Guide to Fix-and-Flip
You've got a property under contract, a contractor ready to walk it, and a closing date that won't wait for a conventional lender's checklist. The house may be a 1970s ranch with a gutted kitchen, questionable wiring, and no realistic path to a standard mortgage appraisal until the work is done. Yet the opportunity is often created by precisely that condition.
That gap is where loans for rehab fit. The right financing can fund acquisition, construction, and carrying costs through a controlled draw process. The wrong structure can turn a workable project into a cash emergency when permits slip, materials cost more than expected, or the resale takes longer than planned. In 2026, the central question isn't whether a lender will approve the deal. It's whether the deal survives a slower exit and a less forgiving margin.
Why Rehab Financing Exists and Who It Is For
A conventional mortgage is designed for a property that can serve as stable collateral on the day it closes. Distressed properties often fail that test. The home may have open walls, unsafe systems, incomplete bathrooms, or a kitchen that has been removed down to the framing. An appraiser can estimate the property's completed value, but a traditional mortgage lender still has to address present condition, habitability, occupancy, and the borrower's ability to qualify under standard income rules.
That creates a timing problem. The seller wants to close now, while the conventional lender wants the property repaired before advancing long-term mortgage capital. A rehab lender accepts that the property is unfinished and underwrites the plan to make it financeable or saleable.
The collateral is the project
Asset-based lenders usually start with the property and the proposed exit. They review the as-is value, the expected after-repair value, the scope of work, the contractor, and the amount of equity supporting the transaction. Personal income and employment can still matter, but they don't carry the same weight they do in a conventional mortgage decision.
This structure suits several borrower profiles:
- House flippers who need acquisition and renovation capital before selling the improved property.
- BRRRR operators who plan to buy, renovate, rent, refinance, and retain the asset.
- Long-term rental buyers facing heavy repairs that must be completed before permanent rental financing is practical.
- Small developers who need acquisition or construction capital to bridge a gap between purchase and a later sale or refinance.
The financing is generally short-term and often interest-only. That makes it useful for a defined project, but dangerous when an investor treats it like a permanent loan. The clock starts at closing, and interest, insurance, taxes, utilities, and other carrying costs continue whether the crew is productive or not.
Practical rule: A rehab loan should be matched to a written project timeline and a credible exit, not just to the purchase price.
The U.S. market shows why this lending channel remains important. ATTOM-based reporting counted about 407,417 flips in 2022, with roughly 41% financed, followed by about 308,922 flips in 2023, with about 39% financed, and around 297,045 flips in 2025, with about 37% financed. Those figures are summarized in ATTOM-based fix-and-flip financing data. Financing isn't a niche feature of the resale market. It supports a substantial number of projects where speed, ARV-based underwriting, and construction draws matter more than a conventional mortgage format.
The Main Types of Loans for Rehab Investors
The product should follow the project, not the other way around. A cosmetic flip, a stabilized rental, a teardown, and an owner-occupied renovation have different timelines, risks, and underwriting requirements.
| Loan Type | Best For | Typical Term | Rate Range | Key Underwriting Metric |
|---|---|---|---|---|
| Fix-and-flip | Distressed acquisitions intended for resale | Short-term project loan | Market-specific | ARV, LTC, scope, and exit |
| DSCR rental | Stabilized rentals held for income | Long-term debt | Market-specific | Property cash flow and DSCR |
| Bridge-to-DSCR | Heavy rehab followed by rental refinance | Short-term bridge plus permanent exit | Market-specific | Completion plan, rent, and refinance value |
| Ground-up construction | Teardown and new residential construction | Construction-period facility | Market-specific | Plans, budget, draw milestones, and finished value |
| FHA 203(k) | Owner-occupants renovating a qualifying home | Long-term mortgage | Program and borrower specific | Property condition, eligible repairs, and occupancy |
Fix-and-flip loans
A fix-and-flip loan is a sprint. The lender advances acquisition money and places renovation funds into a controlled holdback. The loan generally relies on the completed value, the purchase basis, the construction budget, and the expected sale.
It works when the scope is clear and the resale market is liquid enough to support the exit. It works poorly when the borrower has no reserve for a change order or assumes the property will sell immediately after the final inspection.
DSCR and bridge-to-DSCR
A DSCR loan belongs at the stabilization stage, when the property can be evaluated through rent and operating performance. It usually isn't the right first-dollar source for a property that still has exposed framing and no finished systems.
A bridge-to-DSCR structure is a hedge against that mismatch. The bridge funds the acquisition and rehab, while the planned exit is a refinance into long-term rental debt. This approach can make more sense than forcing every project into a sale, particularly when resale timing is uncertain and the finished property has a viable rental profile.
Construction and 203(k)
Ground-up construction financing is for a different risk profile. The lender must evaluate plans, permits, builder capacity, site work, vertical construction, draw milestones, and the finished value. A teardown-rebuild shouldn't be presented as a standard cosmetic flip.
The FHA 203(k) program is built for eligible owner-occupied rehabilitation. HUD identifies a minimum of $5,000 in eligible repairs for the Standard 203(k), while the Limited 203(k) is capped at $75,000 for non-structural work, as described in HUD's 203(k) program guidance. That creates a practical divide between lighter work and larger projects requiring more formal scope control and consultant involvement.
How Lenders Underwrite a Rehab Deal
A lender does not approve a rehab loan from one number. The decision depends on the relationship between value, cost, scope, timeline, and exit. In 2026, that review is also a survivability test. Slower sales, rising carrying costs, and more DSCR buyouts replacing quick flips leave less room for optimistic assumptions.
Start with value and loan sizing
Assume a purchase price of $250,000. The lender reviews the property's condition and estimates its as-is value, then tests the proposed ARV against comparable renovated sales that match the subject in location, size, layout, quality, and condition.
Recent, relevant sales matter more than the highest sale in the neighborhood. A useful ARV package explains why each comparable belongs, how its square footage and finish quality differ, and whether the planned renovation supports the completed price. Investors who need a plain-language explanation can review what ARV means in real estate underwriting.
The lender then applies two central constraints:
- Loan-to-value, or LTV: The loan compared with the completed property value.
- Loan-to-cost, or LTC: The loan compared with acquisition, renovation, and eligible project costs.
For this example, the brief assumes a lender may cap the loan at the lower of 70% to 75% of ARV or 90% to 100% of total project cost. These are underwriting ranges, not promises. A strong ARV cannot repair a weak budget, and a low purchase price cannot make an unrealistic exit workable.
Then audit the budget
A lender needs a line-item scope, not a rounded renovation guess. The budget should separate demolition, framing, roofing, mechanical systems, electrical, plumbing, windows, finishes, appliances, permits, and cleanup. Contractor bids should match that scope and identify who supplies the materials.
The review also covers soft costs and carrying costs. Interest, insurance, taxes, utilities, permits, architectural work, and project management can change the borrower's cash requirement even when they are absent from the headline construction figure.
A contingency reserve belongs in the model. Its size depends on the property's age, how visible the systems are, and how complete the inspection was. If the borrower has not allowed for hidden damage, the lender treats the budget as optimistic.
A loan is only as safe as the weakest assumption inside the scope of work.
Finally, run the margin check. Start with a conservative sale price, subtract selling costs and the projected loan payoff, then account for interest and other holding expenses. The remaining equity should absorb a slower sale, a change order, or a modest appraisal gap. For a DSCR buyout, also test whether the stabilized property can carry the refinance if rents or timing disappoint. If profit exists only under the highest ARV and shortest hold, the deal is not ready for financing.
What 2026 Market Conditions Mean for Rehab Borrowers
The 2026 environment is better understood as a margin-compression year, not automatically as a collapse. The Burns + Kiavi Fix and Flip Market Index fell to 59 in Q2 2026 from 63 in Q1, while 71% of flippers still expected to buy more homes in 2026, according to reported Q2 2026 fix-and-flip survey results. That combination matters. Investor demand can remain active while individual deals become less forgiving.
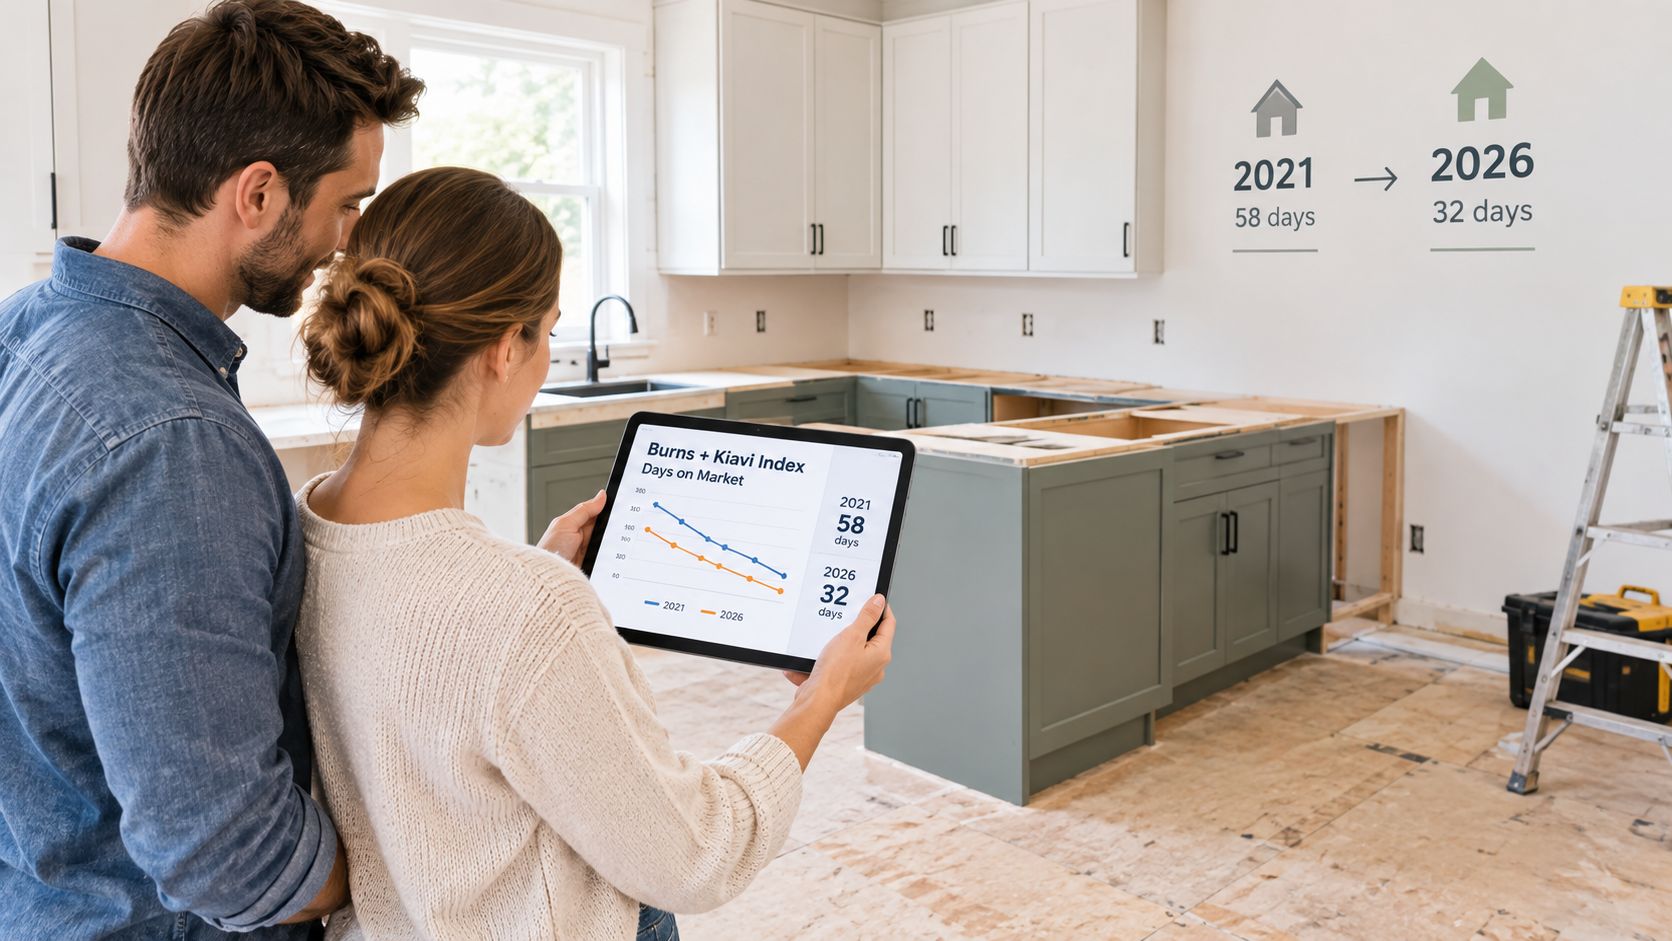
Slower resale creates pressure in three places. The borrower pays interest for longer, the finished property may need additional maintenance or utilities, and a forced price reduction can consume the expected profit. A quick flip and a bridge-to-DSCR project therefore shouldn't be modeled the same way.
Stress-test the exit
Use a conservative underwriting process:
- Reduce confidence in the ARV. Test the deal below the optimistic comparable-supported value rather than treating the appraisal as a guaranteed sale price.
- Add a resale buffer. Give the property time to reach the market, complete listing preparation, receive offers, and close.
- Model a rental exit. If the property can rent after stabilization, calculate whether the projected income supports a DSCR refinance.
- Reserve for the clock. Interest reserves and liquid cash should cover the possibility that construction or resale takes longer than planned.
- Separate profit from liquidity. A project can be profitable on paper and still fail if the borrower can't fund the next draw or monthly carrying obligation.
Recent industry commentary also describes heavier value-add work, including structural renovations and ADU additions, and reports a 14% year-over-year increase in loan amounts earmarked for value-add construction rather than acquisition alone in a 2026 rehab-loan overview. The discussion appears in 2026 rehab-loan market commentary. Bigger scopes make exit flexibility more valuable, but they also make budget discipline and reserves more important.
Qualifying With an Asset-Based Lender
Asset-based underwriting starts with the property, project plan, available equity, and exit. Income documentation still matters, but the lender first tests whether the collateral and transaction can repay the loan if the project runs past its original schedule.
Build a credible borrower file
Credit remains one risk signal among several. At Sims Ventures, a score in the mid-600s can be workable when liquidity, experience, and the overall deal are strong. Lower credit may require more compensating strength, such as substantial reserves, conservative debt, proven construction management, or an experienced operating partner. Disclose credit problems before they surface during underwriting.
Liquidity often determines whether a borrower survives the project. Keep cash available for required equity, closing costs, insurance, carrying expenses, and work that must be completed before a draw is released. Funding the purchase is not enough if a change order, inspection delay, or material increase leaves the borrower unable to cover the next obligation.
Experience can include completed flips, construction management, general contracting, property operations, or a documented relationship with a capable partner. First-time investors can still present a financeable file, but they need a defined scope, an experienced contractor, realistic financing, and clear responsibility for approvals, payments, and site oversight.
Make the scope easy to approve
A lender can underwrite faster when the package answers five questions:
- Scope: What work is being completed, in what order, and by whom?
- Budget: Does every line item have a reasonable cost and supporting bid?
- Permits: Which items require approval, and when will permits be pulled?
- Contractor: Is the contractor experienced, properly insured, and able to manage the schedule?
- Exit: Will the property be sold, rented, or refinanced after completion?
Entity structure also requires care. Investors often close through an LLC, but the appropriate setup depends on title, guaranty, ownership, and state-specific legal requirements. A lender can identify its documentation requirements. Legal and tax questions belong with qualified professionals. For a broader explanation of asset-based mortgage lending, review how collateral-focused borrowing is structured.
Submit the contract, budget, bids, insurance certificates, entity documents, proof of funds, comparable sales, and exit analysis together. Undocumented cash, vague contingencies, uninsured contractors, and major post-appraisal scope changes create avoidable delays and can force a lender to rework the approval. In 2026, rising carrying costs and slower exits make that preparation a survivability issue, not merely a closing convenience.
Timeline, Draws, and What Closing Actually Looks Like
A rehab deal can look profitable on paper and still fail if the timeline leaves the borrower short of cash. In 2026, slower exits and higher carrying costs make closing speed, draw timing, and liquidity part of the underwriting decision. The same discipline matters when a planned sale gives way to a DSCR buyout.
| Phase | Target Duration | Common Stalls |
|---|---|---|
| Initial terms and pre-approval | 24 to 48 hours | Missing contract, unclear exit, incomplete borrower file |
| Appraisal and scope review | 3 to 7 business days | Weak comparables, changing budget, inaccessible property |
| Title and insurance clearance | Depends on third parties | Liens, entity errors, vacant-property coverage |
| Expedited closing | 10 to 15 business days | Appraisal or title delays |
| Standard closing path | 21 to 30 business days | Slow document collection or underwriting revisions |
| Construction draws | 3 to 5 business days per draw after request and inspection | Incomplete work, missing invoices, inspection issues |
| Full project schedule | Often 6 to 9 months for a mid-range gut rehab | Permits, change orders, labor, final appraisal, resale |
From contract to keys
The investor submits the contract, property details, scope, budget, contractor information, comparable sales, and planned exit. The lender issues initial terms, orders or reviews the appraisal, and tests whether the completed value supports the requested loan. Underwriting should also ask how the property survives a delayed sale, higher interest carry, or refinance into DSCR debt.
Title and insurance can become the quiet critical path. A title defect, entity mismatch, or policy that excludes a vacant construction property can stop closing even when the deal economics are sound. Clear those items early, because a missed closing can create extension costs before construction begins.
Once the loan closes, rehab funds are typically held back. The borrower or contractor requests a draw after a defined milestone, an inspector verifies the work, and the lender releases the approved amount. The construction schedule should match those milestones, not informal promises between the borrower and crew. A written construction draw schedule maps work, inspections, and cash needs before demolition starts.
In our experience, holdbacks of 10% to 15% per draw are common until the work is verified or the project reaches completion. The borrower therefore needs working capital even when the approved rehab budget appears sufficient. A budget that funds the work but leaves no reserve can force a pause between inspections and reimbursements.
The deals that stall usually have one of four problems: permits were not pulled early, the contractor changed scope without approval, draw documentation was incomplete, or the final sale appraisal came in below expectations. Build time and liquidity around those risks. If the exit becomes a DSCR buyout, underwrite rent, debt service, and seasoning requirements conservatively rather than assuming a quick refinance will rescue thin margins.
Where Sims Ventures Fits in Rehab Lending
Sims Ventures operates on the private, asset-based side of rehab financing, with a stated footprint across Georgia, North Carolina, South Carolina, and Texas. Its fix-and-flip structure supports acquisition and rehabilitation through a short-term project loan. That structure can work for an experienced operator, but approval still depends on the property, budget, borrower liquidity, and exit plan.
| Loan Type | Max LTV / LTC | Rehab Financing | Typical Term | Best For |
|---|---|---|---|---|
| Fix-and-flip | Up to 75% ARV LTV and up to 90% LTC | Up to 100% of rehab budget | Short-term project term | Experienced operators with a defined resale or refinance exit |
| DSCR rental | Property-specific | Usually for stabilized assets | Long-term rental debt | Investors holding income-producing properties |
| Bridge | Property and scope specific | Acquisition, rehab, seasoning, or repositioning | Short-term | Borrowers moving toward sale or permanent financing |
| Ground-up construction | Project-specific | Draws tied to milestones | Construction-period term | Builders and residential developers |
| FHA 203(k) pathway | Program-specific | Eligible repairs under program rules | Long-term mortgage | Qualifying owner-occupants |
The stated fix-and-flip parameters include up to 90% LTC, 100% of the rehab financed, and ARV-based LTV up to 75%, subject to underwriting. These figures describe potential facility sizing, not the borrower's total cash requirement. Closing costs, reserves, timing gaps, and expenses outside the approved scope still require liquidity.
When the structure makes sense
In 2026, compressed margins and slower exits make the exit decision part of survivability underwriting. An investor who expected a quick sale may instead hold the completed property and pursue a DSCR buyout. That path can convert short-term project debt into longer-term rental debt, but only if the property supports the projected rent and meets valuation, seasoning, condition, and refinance requirements.
Underwrite that transition before closing. Use conservative rent assumptions, allow for a longer carrying period, and test whether debt service remains manageable if the refinance takes longer than planned. A thin resale margin can disappear through interest, taxes, insurance, utilities, repairs, and extension costs before a DSCR loan is ready.
Other financing structures serve different projects. DSCR financing generally fits stabilized rentals, bridge lending can support repositioning, ground-up construction funds new residential projects, and renovation mortgages may suit qualifying owner-occupants. Local appraisal familiarity, title relationships, and draw inspection coverage can matter to investors who operate repeatedly in the same markets.
Sims Ventures can fit experienced operators seeking short-term acquisition-and-rehab capital, a defined resale or refinance exit, and a coordinated process within its four-state footprint. It may fit less well for an investor outside those states or for a small rehab that a local institution can price more cheaply. Compare total cost, execution reliability, liquidity requirements, and exit durability. The headline rate is only one part of the decision.
Lender Checklist and Common Investor Questions
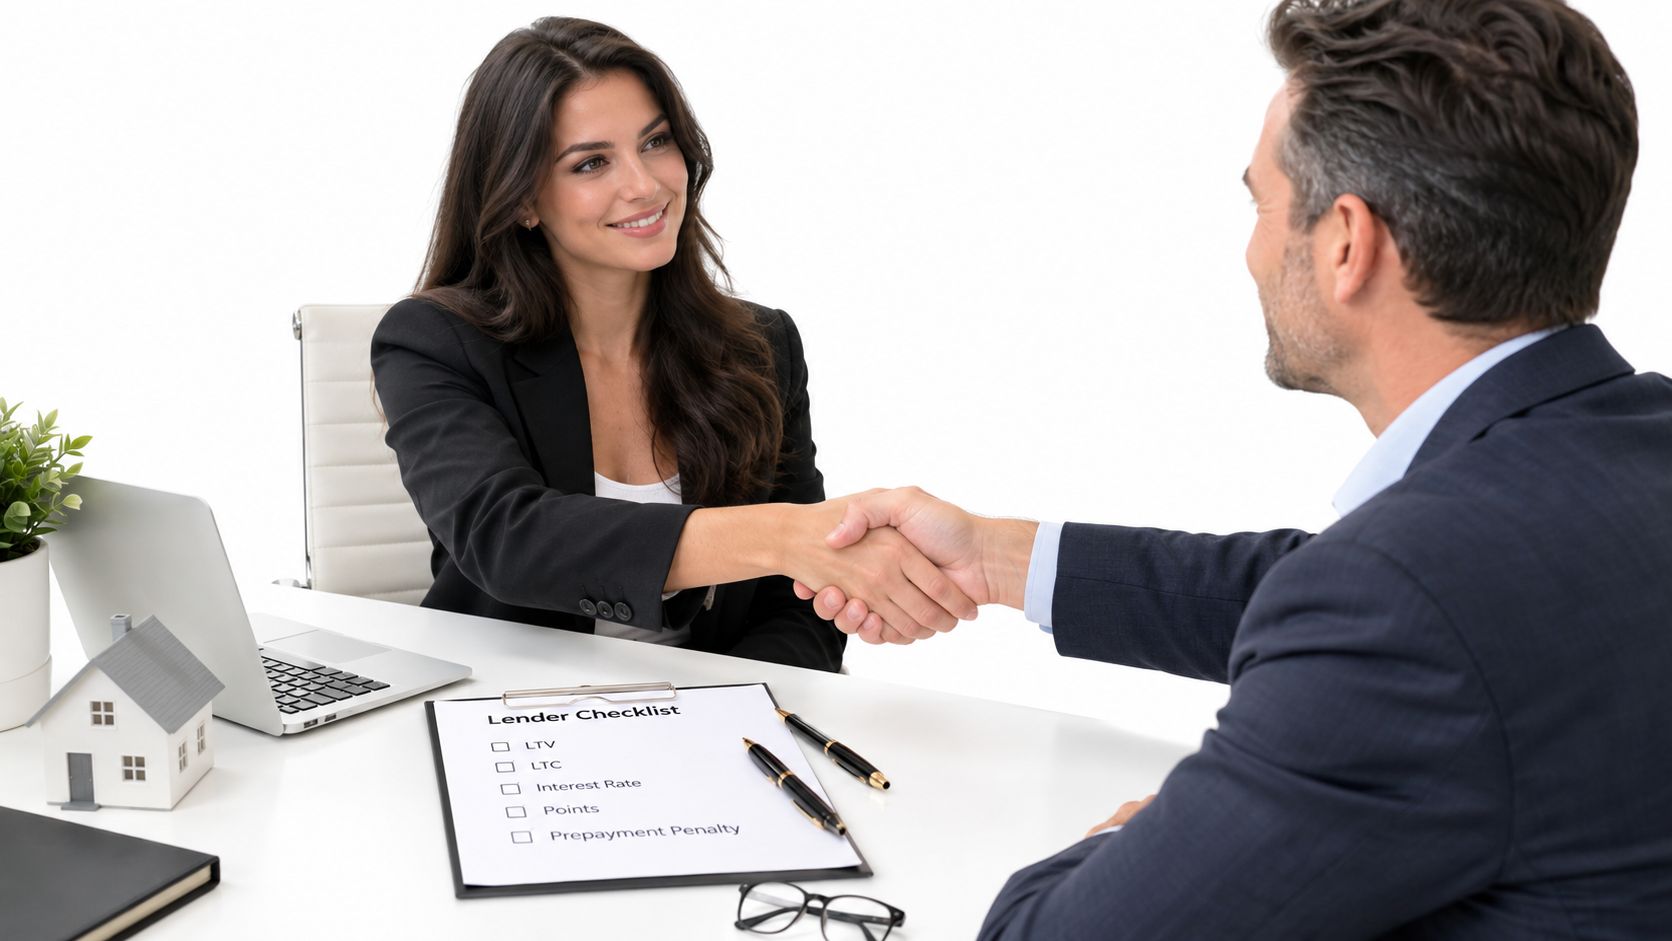
A term sheet deserves the same scrutiny as the property. In 2026, narrower margins, slower exits, and rising carrying costs make loan terms part of the project's survivability plan. Before signing, ask the lender:
- Loan sizing: What are the actual ARV LTV and LTC caps, and which one controls if they produce different loan amounts?
- Rehab funding: Is the full approved budget financed, and which expenses are excluded?
- Cost of capital: What are the interest rate, points, inspection charges, extension costs, and minimum-interest requirements?
- Draw operations: How often can funds be requested, who pays for inspections, and how long does funding take after approval?
- Holdback: What amount remains undisbursed, and what conditions release it?
- Rate protection: Is the rate locked through closing, and what can cause it to change?
- Delay treatment: What happens if construction runs long, the sale takes longer, or a DSCR refinance is not ready?
- Payment terms: Is interest calculated on the full commitment or only on funded balances?
- Exit flexibility: Can the loan be paid off early without a prepayment charge, and can it be extended on transparent terms?
Questions investors ask
Why might a lender require substantial cash down when the product advertises a high ARV LTV? LTV is only one limit. The lender may also apply LTC, require reserves, exclude certain costs, or size the loan below the appraisal to protect against valuation and completion risk.
How do interest-only payments work with construction draws? Loan documents control the answer. Some lenders calculate interest on the outstanding balance, while others use a different commitment or reserve structure. Get the calculation in writing before comparing offers.
What happens if the rehab runs 60 days long? The loan may require an extension, additional interest, and continued insurance and property expenses. The lender may request updated construction status, evidence of remaining funds, or a revised exit plan.
Can an entity borrower bypass personal credit review? Usually not completely. A strong property and entity may reduce reliance on personal income, but lenders commonly review guarantors, liquidity, experience, and credit in the overall risk decision.
Compare at least three quote sheets line by line. A lower rate can lose its advantage through higher points, slow draws, restrictive holdbacks, or expensive extensions. Underwrite the project against the slower exit, including a DSCR buyout if resale timing fails.
Sims Ventures provides fix-and-flip, bridge-to-DSCR, DSCR rental, and ground-up construction financing for investors in Georgia, North Carolina, South Carolina, and Texas, with rehab structures that can include acquisition funding and draw-based construction capital. Review your next project with Sims Ventures and request terms that match the scope, timeline, and exit you can support.
