
Bridge Loan Pros and Cons for Real Estate Investors
You're under contract on a property that makes sense on paper, but the seller wants to close before a conventional lender can finish underwriting. A bridge loan may save the acquisition, preserve your negotiating position, and give you time to renovate or stabilize the asset. It can also turn a good deal into a forced sale if your refinance or disposition plan misses the maturity date.
That's the part most bridge loan pros and cons articles underplay. Speed matters, but exit risk matters more. The right question isn't whether a bridge loan closes quickly or carries a higher rate. It's whether your property, reserves, lender relationships, and backup plan can withstand a delayed sale, slower lease-up, failed appraisal, or postponed refinance.
| Financing question | Bridge loan | Long-term DSCR loan | Construction loan |
|---|---|---|---|
| Primary job | Cover a short-term timing or value gap | Hold a stabilized rental | Fund a ground-up build |
| Underwriting focus | Asset value and exit strategy | Property cash flow and debt service | Budget, plans, builder, and draw progress |
| Main advantage | Speed and flexibility | Longer repayment structure | Controlled funding through construction stages |
| Main danger | Balloon payoff and exit failure | Property cash flow may not support proceeds | Cost overruns and draw delays |
The Deal That Almost Died
An investor in Georgia found a duplex priced below comparable properties. The contract required a 14-day closing, but the investor didn't have enough cash reserves to close without financing. The conventional lender liked the borrower and the property, yet needed roughly 45 days to complete its process. The seller wasn't interested in waiting.
A hard money bridge lender reviewed the collateral, the purchase contract, and the investor's exit plan. The loan funded in nine days. The investor closed, captured the property, completed the work, and kept control of a deal that otherwise would have gone to someone with faster capital.
That's the bridge loan advantage in its purest form. The loan solves a timing problem that a conventional mortgage can't solve.
The investor almost missed the more important issue, though. The bridge carried an interest-only payment, a 12-month maturity clock, origination points added to the payoff, and a default interest clause if the permanent lender failed to close before maturity. None of those terms stopped the acquisition. They determined how much room the investor had after closing.
The closing date saves the deal. The exit plan determines whether the deal survives.
A bridge loan doesn't remove risk. It moves the risk into a shorter window and concentrates it around the payoff date. If the property sells, refinances, or stabilizes as planned, the structure can work well. If the takeout lender delays, the appraisal comes in low, or the renovation runs over schedule, interest and fees can grow while the principal remains outstanding.
That's why I review a bridge loan backward from the exit. Before discussing the rate, I want to know who pays the loan off, what has to happen before that payoff is possible, how long each step takes, and what happens if the timeline slips.
What a Bridge Loan Actually Is
A bridge loan is short-term, asset-based financing used to acquire, improve, hold, or reposition real estate until a sale or longer-term loan becomes available. Unlike a conventional mortgage, it usually relies more heavily on the property's value, condition, and projected exit than on a borrower's standard income profile.
The structure is straightforward:
- The lender advances capital against the property and the approved project scope.
- The borrower makes interest-only payments or allows interest to accrue, depending on the terms.
- The borrower completes the planned transition, such as a sale, renovation, lease-up, or refinance.
- The bridge principal, accrued interest, and applicable fees are paid at maturity or earlier payoff.
Bridge terms commonly run from six to 24 months, depending on the property and strategy. A lender may fund an acquisition, renovation budget, rate buydown, partner buyout, or the gap between two closings. The loan can be especially useful when the property has value but doesn't yet meet the requirements for permanent rental financing.
How it differs from other financing
A conventional mortgage is designed for long-term ownership and typically requires extensive income, credit, debt, and documentation review. Its lower pricing reflects that longer structure, but the process can be too slow for a short-fuse acquisition.
A DSCR loan is also intended for long-term rental ownership, but it focuses on whether property cash flow can support the debt. A bridge loan can be the temporary capital used before the property produces reliable rental income.
A ground-up construction loan serves a different purpose. It releases funds through progress draws, often after inspections confirm that defined construction stages are complete. Bridge capital may help acquire land or an existing property, but it isn't automatically a substitute for a construction facility with a draw schedule and construction oversight.
Terms that deserve scrutiny
Market summaries place bridge pricing broadly around 9% to 14.5% in 2026, while many investment-property transactions cluster near 10% to 12%. Default pricing can add another 2% to 5% over the standard rate, according to recent bridge loan interest rate data.
Origination points, appraisal charges, legal costs, extension fees, and prepayment terms can materially change the all-in cost. Recourse also matters. A non-recourse structure may limit personal exposure, while a recourse loan can leave the borrower responsible beyond the collateral, subject to the contract and applicable exceptions.
The core mechanic is simple: a bridge loan buys time. It's a good loan only when the time has a credible purpose and a realistic endpoint.
The Pros Investors Bank On
Bridge financing earns its place when a property must close before conventional debt can be arranged. The product is built for a short window and a defined exit, not indefinite ownership. UK market data is illustrative of the broader bridging market: a 2025 sample of 1,320 cases reported average completion in 43 days, and more than 40% of surveyed loans funded within three weeks. Broader figures placed average completion around 58 to 59 days in 2022 and 2023, as summarized by bridging loan market statistics.
For US investors, actual timing depends on title, valuation, scope, borrower readiness, and the lender's process. One industry explanation describes common closing windows of 10 to 21 days. It also notes that broker price opinions can reduce the process by roughly three to five days compared with a full appraisal, as outlined in this real estate bridge loan explanation. Treat those figures as market illustrations, not a promise for your transaction.
| Advantage | What it provides for investors |
|---|---|
| Speed | Lets you compete for properties with short closing deadlines |
| Asset-based underwriting | Helps borrowers whose income documentation does not fit bank standards |
| Flexible proceeds | Can combine acquisition funds with approved renovation or repositioning capital |
| Interest-only structure | Reduces monthly payment pressure during construction, rehab, or lease-up |
| Bridge-to-stabilization strategy | Creates a planned path into long-term rental debt |
Speed protects the acquisition
A seller with a firm deadline may reject an offer tied to a slow bank process. Bridge capital lets the investor close first and arrange permanent financing afterward. That advantage matters in off-market purchases, inherited properties, foreclosure-related opportunities, and assets where the seller values certainty over a higher theoretical offer.
Speed only has value when the exit can keep pace. Before signing, identify the refinance lender, sale assumptions, required repairs, valuation method, and fallback source of repayment. A fast closing with no workable takeout plan moves the problem to maturity.
The property carries more weight
Asset-based underwriting can help a self-employed investor with irregular income, multiple entities, or tax returns that fail to show current investment capacity. The lender still reviews experience, liquidity, credit, collateral, and the exit. The property and business plan may carry more weight than a conventional wage profile, but weak collateral will not be rescued by a fast process.
Flexibility supports transitional assets
A bridge lender may structure proceeds around acquisition, repairs, lease-up, or a value-add plan. That can help an investor buy a vacant duplex, complete cosmetic work, improve operations, and refinance after rental performance supports permanent debt.
Interest-only payments preserve cash during the transition, though they do not reduce principal. The borrower still needs reserves for interest, operating costs, repairs, taxes, insurance, and delays. The lower monthly payment is useful only when it supports the project without disguising the balloon payoff.
The strongest use is a bridge-to-stabilization pathway. The borrower closes with short-term capital, completes the business plan, documents improved performance, and transitions into a DSCR loan or sale. Bridge financing works when it has a specific job and a credible endpoint.
The Cons That Bite Later
The deal usually gets expensive after the original exit date passes. Investors often focus on the interest rate and closing speed, then underestimate points, valuation fees, legal charges, extension terms, and the cost of carrying the balance while the sale or refinance remains unfinished. A bridge loan is a short-term solution. The takeout plan determines whether it stays one.
The payment does not reduce principal. Interest-only payments preserve cash during repairs or lease-up, but the borrower can make every payment on time and still owe nearly the original balance at maturity. That payoff must come from a sale, refinance, cash contribution, or another approved source.
Origination points raise the effective cost immediately. A quoted rate may look manageable until points and closing charges are deducted from proceeds or added to the payoff. Review the settlement statement and calculate the net loan proceeds before deciding whether the project has enough equity and operating capital.
The cost of an exit that slips
A delayed exit creates several charges at once. Interest continues, reserves may need replenishment, and the lender may require an updated valuation or revised approval. An extension can also carry a fee and new conditions. Two extra months may sound manageable, but the borrower receives no additional project value while paying to keep the debt outstanding.
| Cost component | Standard terms | Slip scenario impact |
|---|---|---|
| Interest | Higher than permanent debt, as noted earlier | Additional interest continues while principal remains unpaid |
| Origination | Often quoted as points based on the original balance | Charges reduce proceeds or increase the payoff |
| Payment structure | Usually interest-only | Principal remains due at maturity |
| Maturity | Short-term, commonly six to 24 months | A delayed exit can require an extension or create a default |
| Default pricing | May add a percentage to the standard rate | The higher rate applies while the borrower is already under pressure |
Default provisions deserve careful review. Independent market commentary describes default interest increases of 2% to 6% or more after maturity. One market snapshot reported median default interest rates of 18% and stated that 73% of bridge or DSCR defaults charged default interest between 15% and 24.99%, as reported in bridge default interest market commentary.
The contract may also give the lender the right to reassess the property, request updated financial information, or require more reserves before granting an extension. Review the bridge loan requirements before closing, not after the exit starts slipping. Build a written payoff budget that includes the loan balance, accrued interest, points, extension charges, default pricing, taxes, insurance, and operating shortfalls.
Equity exposure adds another layer of risk. If the lender requires substantial equity, the investor has significant capital committed before stabilization. A forced sale in a weak market can consume that equity quickly because selling costs and accumulated loan charges reduce net proceeds. A refinance can create the same problem if the permanent lender values the property below the borrower's projected takeout amount.
The recommendation is straightforward. Set a conservative exit date, price the extension before signing, and keep reserves for a delay. If your deal only works when the property sells on the exact target date, the deal doesn't work yet.
Bridge vs DSCR vs Construction
The right loan depends on what must happen next. A bridge loan buys time for an urgent acquisition or a property in transition. A DSCR loan supports a stabilized rental. A construction loan funds a project through staged draws. Choosing by interest rate alone misses the larger risk: what happens if the exit takes longer than planned.
For this comparison, use the article's earlier bridge pricing framework of 9% to 14.5%. Bridge debt may also include origination points, while DSCR and construction pricing depend on the property, borrower, project, and lender structure. The lowest quoted rate is not automatically the cheapest loan if the wrong product creates a delayed refinance or an unfinished project.
| Loan type | Speed | Rate range | Term | Best for |
|---|---|---|---|---|
| Bridge loan | Fast, often designed for short closing windows | Commonly 9% to 14.5% in this comparison framework | Short-term | Time-sensitive acquisitions and transitional properties |
| DSCR loan | Slower than bridge financing because permanent debt underwriting takes longer | Commonly 7% to 9% in this comparison framework | Long-term, often with amortization | Stabilized rentals held for cash flow |
| Fix-and-flip loan | Fast to moderate | Commonly 10% to 14% in this comparison framework | Often 6 to 18 months in this comparison framework | Light-to-moderate rehab with a sale exit |
| Construction loan | Depends on plans, builder, budget, and approvals | Commonly 9% to 12% in this comparison framework | Project-based | Ground-up development with milestone draws |
Bridge financing
Choose bridge capital when the seller's deadline is shorter than the permanent lender's process, or when the property needs work before it can support long-term debt. The lender may focus on the asset, borrower equity, project scope, and repayment plan instead of requiring the full income documentation associated with a conventional mortgage.
Speed has a price. So does a missed maturity date. Interest, points, extension charges, and carrying costs can turn a temporary solution into expensive debt when the refinance or sale slips.
DSCR financing
A DSCR loan fits an investor holding a stabilized rental and using property cash flow to support repayment. Longer terms and amortization generally make more sense than short-term bridge debt once the property is leased and operating normally.
Review this guide to what debt service coverage ratio means before choosing this structure. The property needs a defensible operating profile. Renovation, lease-up, and uncertain rents weaken the case for permanent rental debt.
Fix-and-flip financing
A fix-and-flip loan suits a defined renovation followed by a sale. It may fund acquisition and approved repairs, with underwriting tied to the after-repair value, budget, timeline, and expected disposition. Use it when resale is the planned exit, not when the property is intended for a long-term hold.
Construction financing
Ground-up construction requires staged funding, not a lump-sum acquisition facility. The lender will review the budget, plans, builder capability, permits, inspections, and controls for project disbursements. Investors planning a Florida residential build can consult this Florida new build financing guide when comparing construction capital with an acquisition bridge.
A bridge loan can cover a land or acquisition gap, but it does not replace a properly structured construction facility. Vertical work creates draw timing, inspection, and completion risks that ordinary bridge debt is not designed to manage. Choose the loan around the exit, then test how the costs change if that exit is delayed.
Three Investor Scenarios Side by Side
The right product becomes clearer when you put the financing against the investor's actual timeline. The loan should match the property's current condition, the borrower's objective, and the event that will repay the debt.
| Scenario | Loan choice | Rate | Monthly payment | Exit |
|---|---|---|---|---|
| Off-market duplex with a 14-day close | Bridge loan | Higher short-term pricing | Interest-only on the outstanding balance | Refinance or sale after improvements |
| Stabilized rental held for years | DSCR loan | 7.5% in the scenario | Long-term amortizing payment | Hold for rental cash flow |
| Ground-up residential build | Construction loan | Within the construction range | Interest on drawn balance, subject to loan terms | Sale or permanent refinance after completion |
Scenario one, the short-fuse purchase
An investor finds a $250,000 duplex off-market. The seller requires a 14-day closing and won't accept conventional financing. A DSCR process that takes 45 to 60 days is irrelevant if the seller walks before approval.
A bridge loan fits because it solves the immediate acquisition problem. The investor should still identify the refinance lender before closing, confirm the property's expected stabilized rents, and reserve enough cash for repairs and holding costs. The bridge is not the investment thesis. It's the temporary mechanism that lets the investor acquire the asset.
Scenario two, the long-term rental
An investor adds a $500,000 stabilized rental portfolio property and expects to hold it for five to 10 years. A DSCR refinance at 7.5% in this scenario provides a long-term structure that can amortize the balance and align payments with rental income.
A bridge loan would create unnecessary maturity pressure after stabilization. The investor doesn't need speed to finish a renovation or solve a closing gap. The investor needs predictable long-term debt.
Scenario three, the new build
A developer controls land purchased with cash and plans a $1.2 million ground-up build over a 14-month construction timeline. The project requires staged funding for vertical construction, inspections, and approved work. A construction loan with an interest reserve and controlled draws fits the project better than a bridge loan with a single acquisition advance.
The construction facility gives the lender and borrower a way to fund progress without pretending the finished property already exists. DSCR debt belongs after completion and stabilization, when the asset can support permanent financing.
When to Use a Bridge Loan and When to Walk
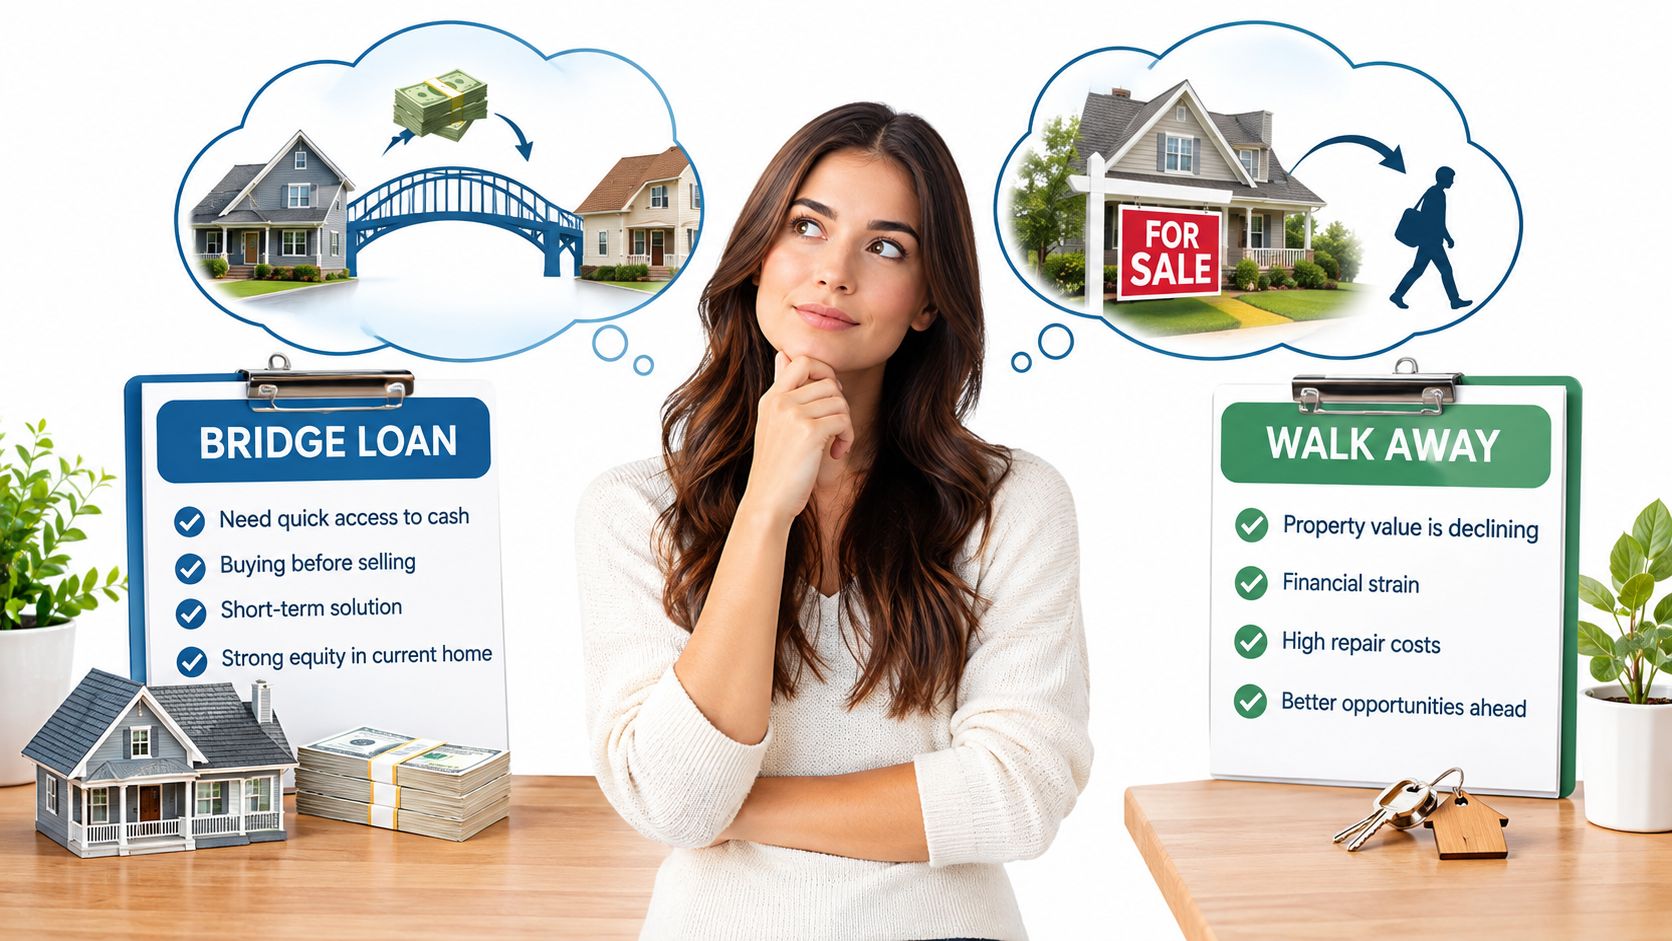
Use bridge financing when timing creates a real opportunity and the exit is already identifiable. The strongest cases involve a short-fuse acquisition, a property that needs cosmetic or moderate work before permanent financing, a bridge-to-DSCR plan, or a partnership buyout where control matters more than the lowest possible rate.
The weakest cases rely on hope. Walk away when the spread between purchase price and stabilized value is thin, the exit depends on appreciation, the sale market is unstable, or no takeout lender has reviewed the deal. A lender's willingness to fund the acquisition doesn't prove that your refinance will close.
The walk-away test
I'd push back on the term sheet if the borrower can't answer these questions in writing:
- Who pays off the loan: Name the sale, refinance, capital event, or partner buyout that retires the balance.
- What must happen first: Identify renovation completion, lease-up, appraisal, seasoning, permits, or other conditions.
- How much time remains: Include underwriting, appraisal, title, closing, marketing, and lender conditions, not just the promised closing date.
- What happens after maturity: Review default interest, extension fees, reserve requirements, foreclosure rights, and notice provisions.
- What is the true all-in cost: Add interest, points, legal charges, inspections, servicing fees, extension costs, and payoff charges.
- Can you survive a delay: Keep a reserve for operating expenses and debt service without relying on an immediate sale.
Review how to get a bridge loan before requesting terms, then bring the lender a complete package. Include the purchase contract, budget, valuation support, rent assumptions, borrower liquidity, construction schedule, and written exit plan.
Negotiate the failure terms before you need them.
Sims Ventures provides asset-based bridge financing, bridge-to-DSCR pathways, DSCR rental loans, fix-and-flip financing, and ground-up residential construction loans for investors in Georgia, North Carolina, South Carolina, and Texas. If you're evaluating a time-sensitive acquisition or need to structure the refinance before closing, visit Sims Ventures to discuss the property, timeline, and exit plan with a private lending advisor.
