
Residential Construction Loan Rates Explained for 2026
You've priced the lot, builder, materials, permits, and projected resale value. Then the lender quotes a construction rate that looks far higher than the mortgage rate you expected. The first reaction is usually, “Is the deal still viable?” The better question is, “What does this loan cost from the first draw through the permanent financing?”
Residential construction loan rates don't work like a standard mortgage coupon. The lender is advancing money against an unfinished asset, releasing capital as work progresses, and managing the possibility of delays, budget changes, incomplete improvements, and an uncertain refinance or sale. Your real cost can therefore be shaped by the rate, draw timing, points, inspections, unused funds, extension terms, and the financing that replaces the construction loan.
This guide breaks down those mechanics in plain English. You'll learn how staged funding works, why investor pricing differs from owner-occupied pricing, which project and borrower details affect the lender's spread, and how to compare offers on an all-in basis. The goal is a financing decision you can defend with your lender, builder, and equity partners, whether you're building in Georgia, North Carolina, South Carolina, or Texas.
Introduction to Residential Construction Loan Rates Today
A builder may receive two quotes for the same house and see a meaningful difference in the headline rate. That doesn't automatically make the lower quote cheaper. One offer may carry heavier documentation, lower borrowing capacity, larger upfront fees, or a conversion structure that exposes the borrower to a new rate later. Another may cost more on the coupon but close faster and keep the project from sitting idle while permits, materials, or contractor availability change.
The market has shown why headline comparisons can mislead. In the U.S. acquisition, development, and construction market, the National Association of Home Builders reported that average effective rates for speculative single-family construction rose from 11.30% in the last quarter of 2022 to 12.59% in the first quarter of 2023, while pre-sold single-family construction moved from 10.85% to 12.01% over the same period. The report also tracks contract rates and initial points, illustrating that construction financing is priced as a package of interest and upfront charges, not merely as a displayed coupon. The NAHB acquisition, development, and construction financing survey provides the underlying context.
For a Southeast investor, the practical task is to build a financing picture that follows the project from dirt to completion. That means asking:
- What rate applies during construction?
- Does the rate float with an index?
- How much capital is available at each milestone?
- When does interest begin?
- Which fees are paid at closing?
- What happens if the build runs long?
- Will the loan convert, refinance, or require a new approval?
Once you view the loan as staged project capital, the quote becomes easier to evaluate. You're no longer comparing a single number. You're comparing the cost and certainty of the entire path.
How Residential Construction Loans Work and Why Rates Differ
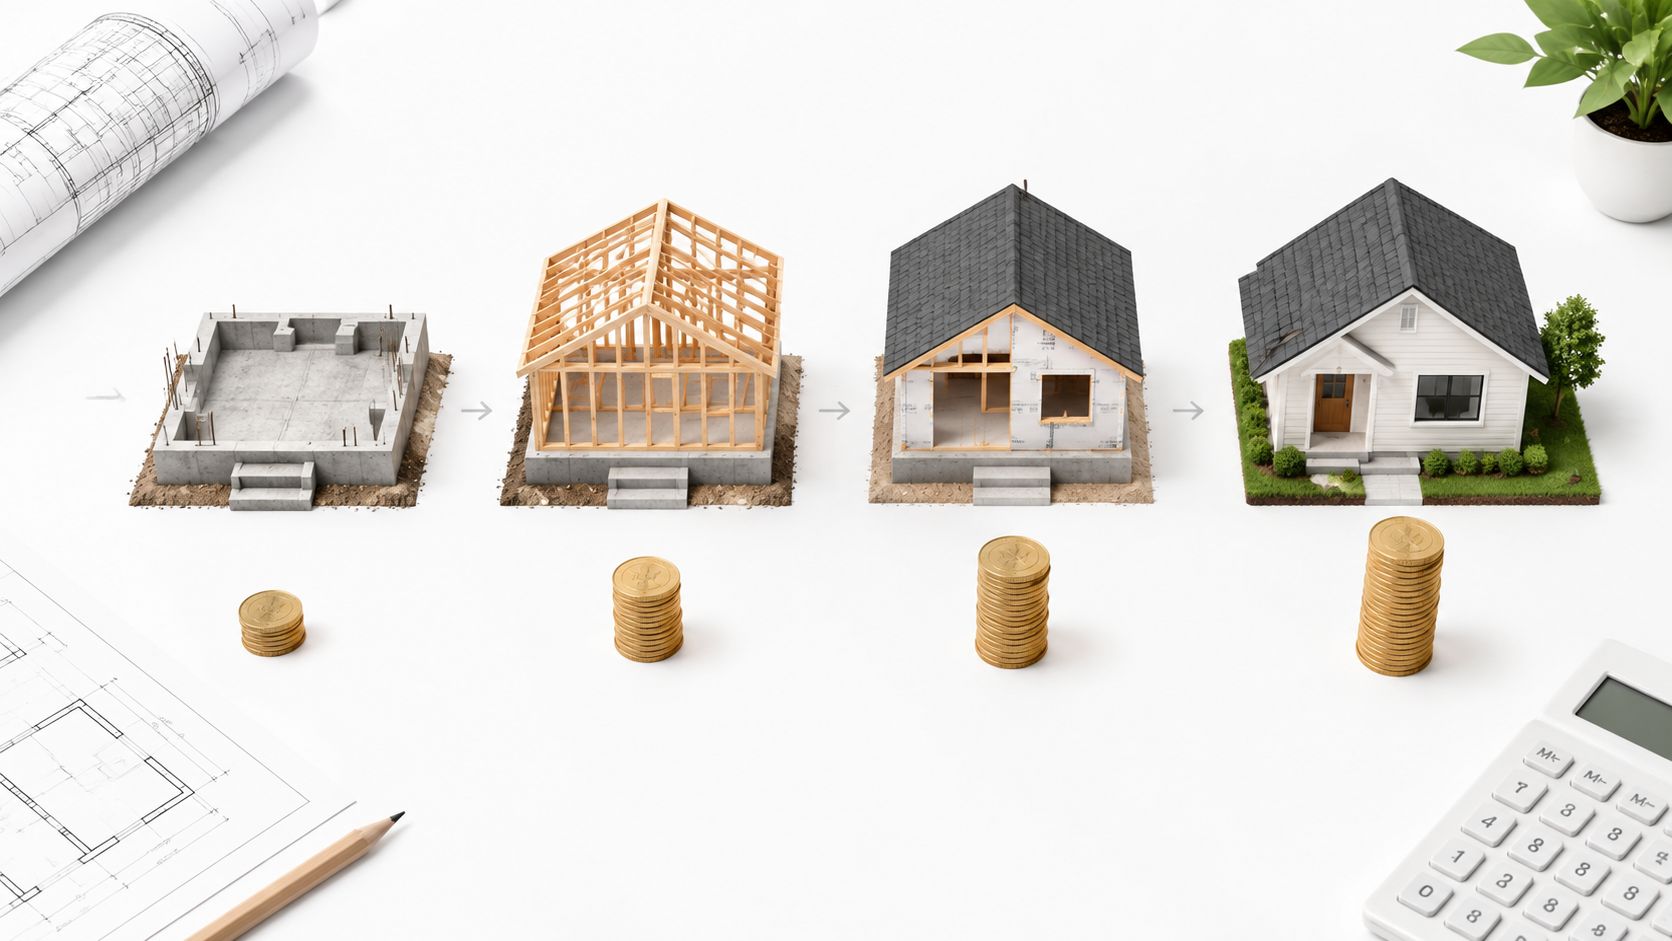
A construction loan finances a home before the home exists as finished collateral. Instead of wiring the entire commitment on day one, the lender usually releases funds through draws tied to completed work. Early funding may support land or site preparation, followed by releases for foundation work, framing, mechanical systems, finishes, and final completion, depending on the approved budget and draw schedule.
The easiest analogy is a lumberyard delivery. You wouldn't pay for every material needed for the entire house before the first truck arrives. You'd pay as materials are delivered and used. A draw-based loan follows a similar rhythm. The borrower generally pays interest on the amount disbursed, not automatically on the full approved commitment, although the loan documents control the exact treatment.
The four moving parts
Interest-only carry is the payment period during construction when the borrower typically services interest while the principal is being advanced in stages. As more of the commitment is drawn, the monthly interest obligation can rise.
The draw schedule connects money to construction milestones. A lender may require a draw request, invoices, inspection, lien documentation, or confirmation that the prior work is complete before releasing the next portion. A delayed inspection or incomplete milestone can delay capital even when the project itself is moving.
Completion risk is the possibility that the borrower, contractor, or budget won't carry the home to the promised finish. Draw risk concerns whether the lender can verify that the requested money matches completed work. Conversion risk concerns what happens when temporary construction debt must become permanent debt or be repaid through a sale.
Those risks explain why a construction loan can carry a meaningful spread over a permanent mortgage benchmark. One survey-based comparison placed Q3 2025 single-family construction loans at 8.34% versus 6.89% for 30-year fixed mortgages, a spread of about 1.45 percentage points. The construction loan rate comparison also highlights why shortening a 9–12 month build period can reduce carry even when the rate itself doesn't change.
Your ability to use financing is another central term. If you're still learning the relationship between project cost and financing, this practical guide to understanding loan to cost can help clarify how lenders view the amount borrowed relative to the total cost basis. For a broader walkthrough of the funding process, review how construction loans work.
What Drives Your Residential Construction Loan Rate
Lenders don't price a construction loan from the market index alone. They combine a benchmark with a project-risk spread, then adjust fees, reserves, guarantees, and conditions around the file. A 2026 market breakdown described a base SOFR of 4.8% and average multifamily residential construction pricing of 7.6%, implying a 2.8% spread over the floating benchmark. This construction loan rate breakdown shows why the all-in rate can change when either the index or the lender's spread changes.
Borrower strength and leverage
Your credit history, liquidity, construction experience, and prior project performance help the lender judge execution risk. A repeat builder with clean financial reporting and completed projects may present less uncertainty than a first-time sponsor with an aggressive budget and limited reserves.
Loan-to-cost, or LTC, matters because it shows how much of the project cost the lender is funding. A lower ratio generally gives the borrower more equity beneath the loan, which can protect the lender if costs rise or the finished value falls short. Loan-to-value can also matter when the lender underwrites the completed property value, especially for an investor exit.
The project itself receives similar scrutiny. A simple, permitted build with a qualified contractor is easier to underwrite than a custom design with uncertain approvals, unusual materials, complicated site work, or a speculative resale plan. A pre-sold home can reduce exit uncertainty, while a spec build leaves the lender dependent on market demand and the borrower's sale or refinance strategy.
Timeline, structure, and documentation
A short, realistic build timeline can reduce exposure to interest carry and market changes. A timeline that depends on several unresolved approvals creates more uncertainty, even if the construction budget looks attractive.
The loan channel also changes the quote. Bank financing may price lower, around 8% to 9%, but independent market guidance describes requirements such as heavier documentation, personal guarantees, and near 75% LTC. Private structures can move into double-digit pricing when the file involves greater execution, documentation, or exit risk. This investor construction lending overview explains why similar homes can receive different pricing when the borrowers and financing models differ.
| Rate Driver | Lower Rate Signal | Higher Rate Signal |
|---|---|---|
| Sponsor profile | Demonstrated building experience, liquidity, clean reporting | Limited experience, thin reserves, unresolved credit concerns |
| LTC and value | More borrower equity, supportable completed value | High leverage, aggressive value assumptions |
| Timeline | Permits ready, clear milestones, reliable contractor | Open approvals, compressed schedule, uncertain completion |
| Loan structure | Transparent budget, defined exit, appropriate reserves | Unclear takeout, complex terms, weak contingency planning |
| Property plan | Straightforward design, strong market fit, pre-sale support | Highly customized spec build or uncertain resale demand |
| Documentation | Complete plans, contracts, budget, and financial package | Missing documents, changing scope, inconsistent figures |
Before applying, prioritize the improvements you can control quickly. Finalize the plans and budget, verify the contractor's scope, document available equity, define the sale or refinance exit, and ask each lender to separate the benchmark, spread, points, inspection charges, extension terms, and conversion provisions.
Conventional Versus Private and Hard Money Construction Financing
The lowest advertised coupon may not be the right target for every builder. Conventional lenders often want a complete borrower file, detailed income documentation, personal guarantees, conservative financing, and a construction plan that fits established approval procedures. That structure can work well for an owner-occupied borrower or experienced sponsor who has time to assemble the package.
Private and hard money lenders generally focus more heavily on the collateral, project economics, sponsor contribution, construction plan, and exit strategy. That flexibility can help self-employed builders, investors with irregular income, and borrowers pursuing time-sensitive opportunities. The trade-off is usually a higher rate or fee structure, because the lender is accepting a different risk profile and underwriting model.
The distinction matters in Georgia, North Carolina, South Carolina, and Texas, where an investor may be building a rental, a resale home, or a small portfolio of projects. A borrower who needs an asset-based decision may value execution certainty more than a bank's lower initial coupon. A borrower with strong traditional documentation and a flexible closing timeline may prefer the conventional path.
Compare the financing package
| Feature | Conventional Bank | Private Hard Money |
|---|---|---|
| Primary underwriting focus | Borrower documentation plus project | Asset, collateral, project, and exit |
| Pricing tendency | Often lower, around 8% to 9% in cited independent guidance | Can reach double digits for higher-risk structures |
| Leverage | May use tighter caps, such as roughly 75% LTC | Varies by deal strength, collateral, and sponsor equity |
| Guarantees | Personal guarantees are commonly requested | Structure varies, with deal-specific guarantees |
| Documentation | More extensive income, tax, and financial records | Often more asset and project focused |
| Speed | Approval can require a longer review process | Can suit time-sensitive closings |
| Best fit | Documented borrowers with a predictable timeline | Investors needing flexibility or alternative underwriting |
The right comparison isn't “bank versus private” in the abstract. It's whether the structure matches the project's actual constraints. A bank may be a strong fit when the plans are complete, the borrower's income is easy to document, and the schedule allows for a detailed review. Private financing may make more sense when the borrower's strength sits in the property and execution plan rather than conventional income records.
Smaller projects can also have unique needs. If you're evaluating an accessory dwelling unit, a focused ADU construction loan guide can help you think through how the project type affects financing requirements.
Practical rule: Choose the financing channel that protects the project's critical path, not simply the quote with the smallest headline number.
Qualifying Draw Schedules and Converting to Permanent Financing
A construction loan application starts with the deal as a whole. The lender needs to understand who owns the project, who will build it, what it will cost, what it should be worth when complete, and how the temporary debt will be repaid. For an investor, that usually means presenting an entity structure, contractor agreement, plans, permits or approval status, line-item budget, equity contribution, and a credible sale or refinance plan.
The future value appraisal deserves careful attention. Because the finished home doesn't exist yet, the valuation relies on plans, specifications, comparable properties, and the expected completed condition. A budget that looks attractive against an unsupported value won't create a dependable borrowing base.
From approval to the first draw
The process typically follows a practical sequence:
- Underwriting reviews the sponsor and deal. The lender tests equity, experience, liquidity, credit, project economics, and exit feasibility.
- The budget becomes the control document. Changes to scope, materials, or contractor costs may require approval before the lender releases additional funds.
- The draw schedule matches visible progress. The builder requests funds after completing defined work, and the lender or inspector verifies the milestone.
- The borrower carries interest as funds move. Early draws create less interest expense than later draws, but delays can extend the period before the home produces sale or rental income.
- Final completion supports the takeout. The project must satisfy the lender's completion requirements before conversion, refinance, or sale proceeds can retire the construction debt.
Some lenders include interest reserves, which set aside loan proceeds to cover interest during the build. That can protect operating liquidity, but it doesn't make the cost disappear. The reserve is still part of the financing structure and should appear in the borrower's project-level analysis.
Review the mechanics of milestone-based funding in this construction draw schedule. Ask whether inspections, lien releases, title updates, retainage, and change orders can delay the next advance.
Conversion and rate resets
A construction-to-permanent loan may convert under defined conditions, while a separate construction facility may require a new refinance approval. Some structures permit a rate lock for the future mortgage. Others leave the permanent debt subject to market pricing when the home is complete.
Read the extension and reset language before closing. If the build runs long, the temporary rate may continue, an extension fee may apply, or the borrower may need to provide updated financial and project information. A delay at the draw stage can become a financing issue at conversion, so the takeout plan belongs in the initial underwriting package.
Practical Ways to Secure a Lower All In Cost
A lower coupon helps, but it's only one lever. The borrower can also reduce cost by shortening the period of outstanding debt, avoiding idle draw requests, negotiating fees, and selecting a conversion structure that fits the expected completion date.
Start with the schedule. A contractor who can sequence work reliably may reduce interest-only carry by preventing the loan from remaining open after the home is ready for sale or refinance. That doesn't mean rushing construction. It means removing avoidable gaps between inspections, draw requests, subcontractor payments, and the next milestone.
Improve the cost equation before closing
- Tighten the budget: Separate hard costs, soft costs, contingency, financing fees, and reserves so the lender can see where money goes.
- Strengthen the equity position: Additional borrower capital can reduce borrowing and may improve the lender's view of loss protection.
- Prepare the sponsor package: Organize experience, liquidity, entity documents, contractor information, and the exit plan before requesting terms.
- Compare the spread: If pricing is benchmark plus a spread, ask lenders to identify both components rather than comparing only the all-in figure on one day.
- Negotiate points and fees: A lower rate with heavier points may not beat a higher rate with fewer upfront charges, especially when the build is short.
- Plan the takeout early: Decide whether the exit is a sale, permanent mortgage, or bridge-to-rental refinance before construction begins.
One 2026 guide describes construction loans as commonly running 1 to 2 percentage points above standard mortgage rates, with many borrowers landing in the 7.5% to 9% range. The same guidance contrasts those figures with owner-occupied construction-to-permanent examples around 5.875% to 6.875%, while investor-focused structures may be described at 8% to 11.25% or more. This construction loan guide shows why the words “construction loan rate” don't identify one uniform product.
Cost test: Put the rate, points, origination charges, inspection fees, draw fees, reserve treatment, extension terms, and expected conversion rate into one project worksheet.
For investors comparing financing options, construction loan interest rate guidance can help frame the questions to ask. Sims Ventures offers ground-up residential construction financing and builder-focused credit options for investors in its service markets, with structures that use milestone-based draws and may use floating pricing.
During construction, protect the schedule you underwrote. Submit complete draw packages, communicate scope changes before work begins, keep lien documentation current, and track remaining budget against completed work. The cheapest financing is often the loan that closes on time, funds predictably, and exits without an expensive extension.
Real World Scenarios That Show Rate Differences in Action
Consider two borrowers building similar homes in the Southeast.
The first is an owner-occupant with complete income documentation, a defined builder contract, strong equity, and a straightforward construction-to-permanent plan. The lender can evaluate the borrower through a familiar documentation model, and the project presents limited speculative resale risk. The rate may land closer to owner-occupied construction-to-permanent pricing, though the borrower still needs to review draw rules, fees, and conversion terms.
Owner-occupied lesson: A lower quote is useful only if the borrower can satisfy the documentation, leverage, and timing requirements attached to it.
The second borrower is an investor building a spec home through an entity. The investor may have substantial real estate experience but irregular personal income, a higher requested loan position, and a resale exit that depends on local demand. Asset-based financing may provide a workable path, but the lender may charge a higher spread, require more equity, or impose tighter controls around draws and completion.
The same floor plan can therefore produce different economics. The difference isn't necessarily the house. It's the combination of borrower profile, project certainty, documentation, and exit risk.
A faster draw process may protect the investor from contractor downtime, while a bridge-to-DSCR exit may provide a defined path into rental debt after stabilization. Neither choice is automatically cheaper. The borrower should compare the full cost against the value of speed, flexibility, and a dependable takeout.
Investor lesson: Underwrite the financing decision as part of the business plan. A higher rate can be acceptable when it solves a timing or documentation constraint, but the project must still support the complete cost of capital.
Frequently Asked Questions About Timing and Loan Structure
How long does a construction rate quote last?
A quote may be valid only for a defined period, especially when pricing is tied to a floating benchmark. Ask when the terms expire and whether the lender can refresh them before closing.
Does the rate float during draws?
It can. Some loans use a benchmark plus a spread, so the all-in cost can change as the index moves. Confirm the index, adjustment frequency, floor, and spread in writing.
What happens if construction runs long?
The lender may extend the loan, charge an extension fee, revise pricing, or require updated underwriting. Review those provisions before the first advance.
Do draw schedules change monthly payments?
Usually, interest rises as more principal is advanced. A delayed draw may reduce current interest, but it can also delay construction progress and the eventual exit.
Can conversion reprice the loan?
Yes. A conversion may use a locked rate, a predetermined formula, or market pricing at completion. Ask what happens if the build misses its expected completion date.
For a project in GA, NC, SC, or TX, compare financing against the complete build schedule, not just the initial quote. Gather the plans, budget, contractor details, equity evidence, and exit strategy before requesting final terms.
Sims Ventures provides asset-based financing for ground-up residential construction, rental properties, and investment projects across Georgia, North Carolina, South Carolina, and Texas. Visit Sims Ventures to discuss a construction structure that fits your draw schedule, project economics, and permanent financing plan.
